
SEPT 17 – For years, many African payment systems were built around one basic problem: how to move money from one person to another quickly and cheaply.
Mobile money changed that equation across the continent, bringing millions of people into electronic payments and making financial services available far beyond traditional bank branches.
The next problem is more complicated.
Once money has been sent, institutions still need to know what the payment was for, who made it, which invoice it belongs to, whether the beneficiary details were correct and whether the transaction eventually reached the right account.
That challenge is becoming increasingly important across government revenue, logistics, professional associations, agricultural payments and other parts of African commerce where moving money is only one stage of a much larger transaction.
South Sudan offers an interesting example of how that change began.
Before electronic tax administration expanded, businesses in South Sudan frequently dealt with systems that depended partly on physical visits, spreadsheets, paper records and processes that did not always communicate easily with one another.
For government, that made revenue administration harder because identifying taxpayers, matching payments and bringing information together across different offices could take considerable time.
The National Revenue Authority later moved towards electronic tax administration, allowing taxpayers to register, file returns and make payments through digital systems.
Crawford Capital was involved as a technology solution provider during the development of the electronic tax platform, with banks connected to the system so transactions could be recorded and matched more efficiently.
Customs systems were digitised as well, bringing business information, taxpayer records and collections into processes where officials could check transactions electronically rather than relying entirely on separate manual records.
The result was a very different kind of revenue environment.
A transaction could increasingly carry a reference number, taxpayer identity, payment history and electronic record that could be checked after the money had moved.
South Sudan’s non-oil revenue later increased substantially as tax administration reforms continued.
Electronic tax and customs systems were only part of those reforms, since staffing, enforcement, policy decisions and stronger compliance monitoring contributed as well.
Still, digitisation gave revenue authorities something basic but important: better information about who should pay, what had been assessed and whether the payment had actually been completed.
That matters in any financial system because money that cannot be matched properly can create problems even when the payer has done everything correctly.
A business may have paid, but the responsible institution still needs to know which invoice was settled and whether the amount corresponds with the service being provided.
That lesson is now becoming relevant far beyond government tax collection.
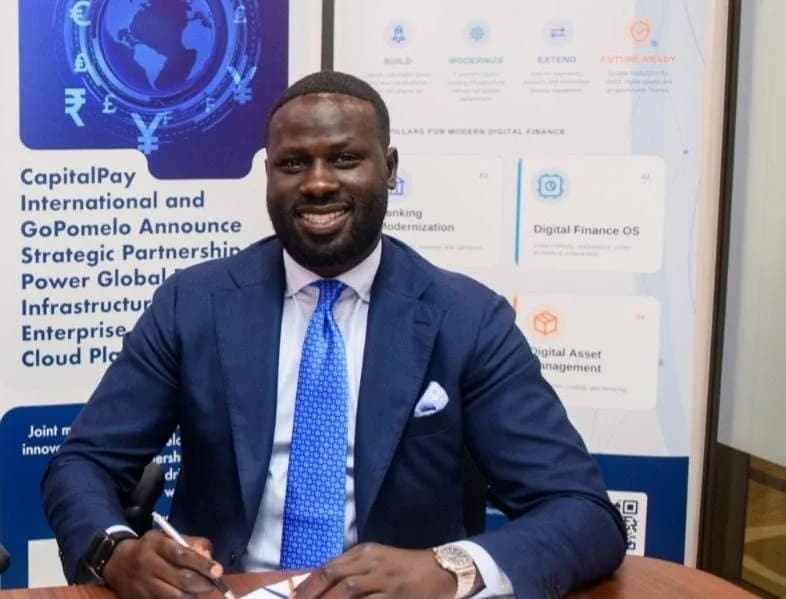
Garang Mayom Malek’s more recent work through CapitalPay International is moving into areas where the same transaction problems appear across trade, logistics and professional payments.
Rather than concentrating mainly on consumer wallets, CapitalPay is positioning itself around payment infrastructure used by institutions that need transactions to be identified, checked and matched with specific services.
The distinction is important because an institutional payment normally carries much more information than a simple transfer between two individuals.
A logistics payment, for example, may need to correspond with a particular clearing agent, shipment, invoice, licence or cargo transaction before the wider process can continue.
Sending the money is therefore only the beginning.
The payment must also be recognised correctly by the institution expecting it.
In Kenya, CapitalPay has been working with the Kenya International Freight and Warehousing Association around a proposed system for licensed clearing and forwarding agents.
The idea brings together professional records, payments, compliance information and transactions connected to cargo handling.
That type of system addresses a problem familiar across logistics, where a payment that cannot immediately be matched with the correct agent or invoice can hold up an otherwise completed transaction.
When payment records, professional information and transaction references sit inside the same system, the organisation receiving the money has a better chance of identifying exactly what each payment relates to.
For freight operators, that can mean fewer disputes and less time spent searching for transactions that have already left the payer’s account.
Agricultural payments create another challenge entirely.
A cooperative making payments to large numbers of farmers can encounter incorrect account details, duplicate beneficiary records, mismatched names or payments directed to accounts that cannot receive them.
Finding those problems after a large payment batch has already been released can create delays for farmers and additional work for the organisation responsible for correcting the transactions.
Systems that check beneficiary information before money is released can reduce some of those failures, while transaction records make it easier to identify what happened when a payment does not arrive as expected.
CapitalPay’s proposed work around professional payments and agricultural transaction systems in Tanzania sits inside this wider problem.
The value is less about creating another wallet and more about helping institutions manage large numbers of payments without losing track of the people, invoices or services attached to them.
This represents a wider change taking place across African financial technology.
The first generation of payment companies competed heavily around the consumer experience, where the main question was how quickly somebody could send money or pay a merchant.
Institutional payments create different demands.
A freight association may need membership and compliance information attached to a transaction.
A cooperative may need thousands of beneficiary details checked before payments are released.
A government institution may need an electronic record connecting a payment with a particular tax obligation or public service.
A logistics operator may need confirmation that an invoice has been settled before cargo can move.
Those are not simply payment problems.
They are information, identification and reconciliation problems sitting around the movement of money.
Africa’s growing digital economy means more organisations will eventually face the same basic question: once somebody has paid, how quickly can the receiving institution understand exactly what that money relates to?
That is where payment infrastructure is beginning to move beyond the familiar consumer wallet.
Companies working in this area will increasingly compete around transaction matching, settlement records, compliance information, institutional connections and the ability to handle large numbers of payments without creating administrative confusion.
For CapitalPay, the opportunity is to take experience built around institutional payment systems and apply it across African industries where money moves between businesses, professional bodies, banks, government agencies and large groups of beneficiaries.
The success of that model will ultimately be visible in very practical results, including fewer failed payments, quicker matching of transactions, shorter reconciliation periods and clearer records for the organisations using the systems.
Africa’s first digital finance boom changed how people sent money.
The next one may be about making sure that after the money arrives, everybody involved knows exactly where it came from, what it paid for and what should happen next.


Comments
No comments yet. Be the first to share your thoughts.