
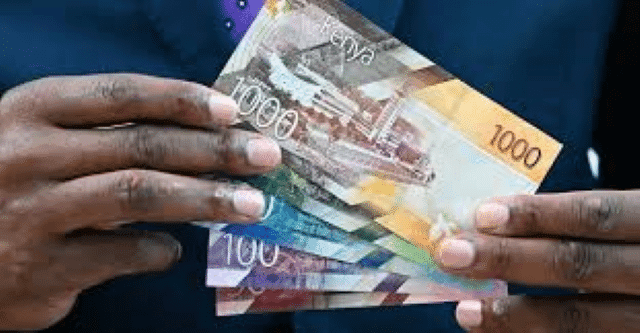
Building wealth is not just about how much money you earn. It is about how you manage it, the decisions you make and the habits you develop over time. You can earn a good salary and still struggle financially if you spend everything you make. Equally, someone with a modest income can gradually build wealth by saving consistently, investing wisely and avoiding unnecessary debt.
Financial literacy gives you the knowledge and skills to make informed decisions about your money. Whether you are employed, self-employed or running a business, these 10 lessons can help you build a stronger financial future.
1. Spend Less Than You Earn
One of the most important principles of wealth creation is ensuring that your expenses do not consume all your income. When your spending matches or exceeds your earnings, there is little room to save, invest or prepare for emergencies. Track your income and expenses to understand where your money goes.
Create a realistic budget that covers your needs, financial goals and some enjoyment. The aim is not to eliminate every pleasure but to spend intentionally and consistently create a surplus.
2. Pay Yourself First
Do not wait until the end of the month to save whatever remains. Often, nothing will be left.
Instead, set aside money for savings and investments as soon as you receive your income. Automating contributions can help you remain consistent.
Start with an amount you can sustain and increase it as your income grows. Consistency matters because the money you save today can become the foundation for future investments and financial security.
3. Understand the Difference Between Assets and Liabilities
Wealth grows when you accumulate assets that generate income, appreciate in value or help reduce future expenses.
Examples may include shares, bonds, income-generating property and ownership in profitable businesses. Liabilities, such as loans and other financial obligations, require money to service.
However, not every asset automatically makes you wealthy. Property can incur maintenance costs, shares can lose value and businesses can fail. Learn to assess the costs, risks and potential returns before committing your money.
4. Make Compound Interest Work for You
Compounding occurs when returns generate additional returns over time. The longer your money remains invested and earns positive returns, the greater the potential effect.
For example, if you invest KSh 100,000 and earn a hypothetical 8% annual return, compounded annually, it could grow to approximately KSh 215,900 after 10 years, before fees and taxes. Actual returns are not guaranteed.
Start investing as early as reasonably possible, reinvest returns where appropriate and avoid withdrawing your investments unnecessarily.
Money: The Power Of Compound Interest
5. Learn the Difference Between Good Debt and Bad Debt
Debt is not always harmful, but it can undermine wealth creation when used carelessly.
Borrowing to fund a productive business or acquire an income-generating asset may make financial sense if the expected benefits justify the costs and risks. Expensive consumer debt, particularly high-interest borrowing to finance a lifestyle, can be more damaging.
Before taking a loan, examine the interest rate, fees, repayment period and total amount payable. Ensure repayments fit comfortably within your budget, even if your income falls temporarily.
Not All Debt Is Bad. How To Use Debt To Grow Your Wealth
6. Build an Emergency Fund
Unexpected expenses can derail your financial plans. Medical bills, job losses, urgent repairs or interruptions to business income may force you to borrow or sell investments at an unfavourable time.
Build an emergency fund in an accessible, relatively low-risk account. A common target is three to six months of essential expenses, although your circumstances may require more or less.
Start with a smaller amount if necessary and build gradually. An emergency fund gives you breathing room when life does not go according to plan.
Finances: The Importance Of An Emergency Fund
7. Understand the Power of Investing and Diversification
Saving protects money for future use, while investing offers the potential for growth over the long term, although it involves risk.
Learn about different investment options available in Kenya, including Treasury bills and bonds, regulated collective investment schemes, shares, pension arrangements and property.
Understand each investment’s risks, fees, liquidity and expected time horizon. Diversifying across suitable assets can reduce dependence on one investment, although it cannot eliminate all losses.
Verify providers and investment products with the relevant regulators, and be cautious of schemes promising unusually high or guaranteed returns.
8. Protect Your Wealth With Insurance
Building wealth is only part of the equation. Protecting it matters, too.
An unexpected illness, accident, death or major property loss can wipe out years of savings. Depending on your circumstances, consider appropriate health, life, disability, motor or property insurance.
Understand what each policy covers, its exclusions, premiums and claims requirements. Insurance is designed to transfer specified risks, not to guarantee wealth creation.
Using Insurance For Wealth Management: How Insurance Can Help You Build And Protect Wealth Over Time
9. Avoid Lifestyle Inflation
When your income increases, it is tempting to upgrade your home, car, wardrobe and spending habits immediately.
Lifestyle inflation occurs when spending rises alongside income, leaving little extra money to build wealth. You can enjoy the rewards of your hard work without spending every additional shilling.
When you receive a raise, bonus or additional business income, direct a portion towards investments, savings or debt repayment before increasing discretionary spending.
Lifestyle Creep: How Your Growing Income Can Sabotage Your Financial Goals
10. Invest in Your Financial Education
Financial literacy is an ongoing process. Learn how interest rates, inflation, taxes, investment risks and retirement planning affect your money.
Read credible financial resources, compare products and ask questions before making significant decisions. Avoid investing in something you do not understand simply because friends, influencers or colleagues recommend it.
Be particularly wary of pressure to act quickly, referral-driven investment schemes and promises of effortless wealth.
Why Are We So Bad With Money? Would Financial Education In Schools Help With This Issue?
Final Thoughts
Building wealth is rarely about one brilliant financial decision. It is usually the result of consistent habits, informed choices, patience and the ability to manage risk.
Start by understanding your finances, spending less than you earn, saving consistently and investing according to your goals. Protect what you build and review your progress regularly.
Remember: earning money creates an opportunity, but managing it wisely helps you turn that opportunity into lasting wealth.
Check out
Are You Sabotaging Your Wealth Building Journey? Heres How To Recover
Personal Finance: How To Overcome Black Tax And Grow Generational Wealth

Comments
No comments yet. Be the first to share your thoughts.