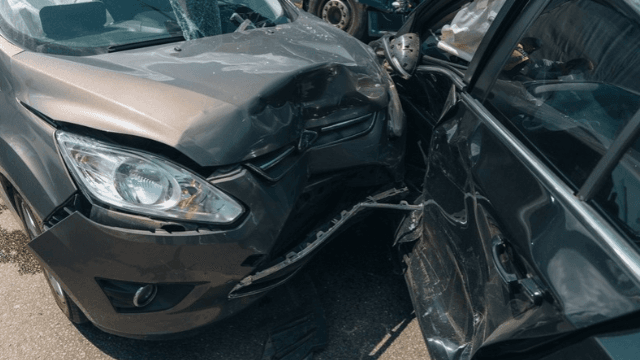
A settlement offer can look like a way to put a car crash behind you until the numbers fail to cover the bills left on the table. Medical visits, missed work, and car repairs can cost far more than an insurer’s first offer suggests. In Austin, Texas, drivers may feel pressure to accept money quickly, especially while expenses keep arriving. Yet an offer is not the same as a fair picture of every loss. A car accident attorney in Austin may review the claim and explain the options available, while the right next step depends on the facts and paperwork.
Why an Insurance Offer May Fall Short
Insurance companies review claims using the records and details they receive. Missing information can mean an offer does not reflect the full cost of a crash. The insurer may also question who caused the collision or how serious an injury is. Multi-car crashes can make the facts harder to sort out.
Repair bills are easy to count. Follow-up care, missed work, and limits on daily activities may take longer to assess. If the insurer has not received records that support these losses, its offer may be based on an incomplete view.
Check the Offer Before Responding
Compare the offer with crash-related costs. Look for missing bills or losses, ask about unclear amounts, and keep copies of letters, estimates, and claim forms.
Pay attention to any release included with the offer. Signing it may end the claim and prevent you from asking for more money for the same crash. Do not sign only because the insurer says the offer is available for a limited time. Read the terms and seek qualified help if you are unsure what they mean.
Steps That May Support a Settlement Challenge
A clear response connects the amount requested to records and facts. Stay organized and avoid guessing about costs. Useful steps may include:
- Collect records: Save medical bills, treatment notes, repair estimates, photos, and the crash report.
- Record lost income: Keep pay stubs or an employer statement showing time missed because of the collision.
- List other losses: Note travel for treatment and other expenses tied to the crash, keeping receipts.
- Send a written response: Explain why the offer seems too low and attach records supporting the amount requested.
- Keep communication records: Save messages and note the date and name of each insurance representative you speak with.
Give the insurer time to review your factual response. A counteroffer cannot guarantee more money, but it makes the reasons for disagreement clear. If treatment is ongoing, explain that the final cost may not be known yet and ask how the insurer will consider updated records. Do not assume the company will reopen a claim after you sign a release.
How Texas Rules May Affect Your Options
Texas law can affect a car accident claim’s value and the time available to file a lawsuit. Texas uses a modified comparative responsibility rule. In many injury cases, a person may recover damages if they are not more than 50 percent responsible, although compensation can be reduced by their share of fault. Its application depends on the claim.
Texas generally sets a two-year deadline for filing a personal injury lawsuit, though exceptions may apply. This court deadline differs from an insurer’s response date, and waiting too long can affect options. Claims involving government vehicles or other special situations may have different notice rules. Check which rules apply to your claim.
Mistakes That Can Weaken a Dispute
Rushing through paperwork can make a low offer harder to challenge. Avoid guessing about symptoms, leaving out costs, or giving different accounts of the crash. Keep medical appointments, follow your providers’ instructions, and save records. Be careful about posting crash details online, as statements may be used later.
Do not treat a phone conversation as the final record of an agreement. Ask for important terms in writing, read each document, and keep copies of anything you sign. If the insurer will not explain its calculations, record what was said and request a written breakdown.
Make the Decision With the Full Picture
A low offer does not have to be accepted without review, but challenging it takes clear records and careful reading. Austin drivers can compare the offer with documented medical costs, missed income, vehicle repairs, and other losses linked to the crash. They should check whether a release would close the claim and keep filing deadlines in mind.
A car accident attorney in Austin may help review the insurer’s position and explain possible next steps. No response guarantees a better result. Before agreeing to a final settlement, read the offer and its terms carefully.
Comments
No comments yet. Be the first to share your thoughts.