
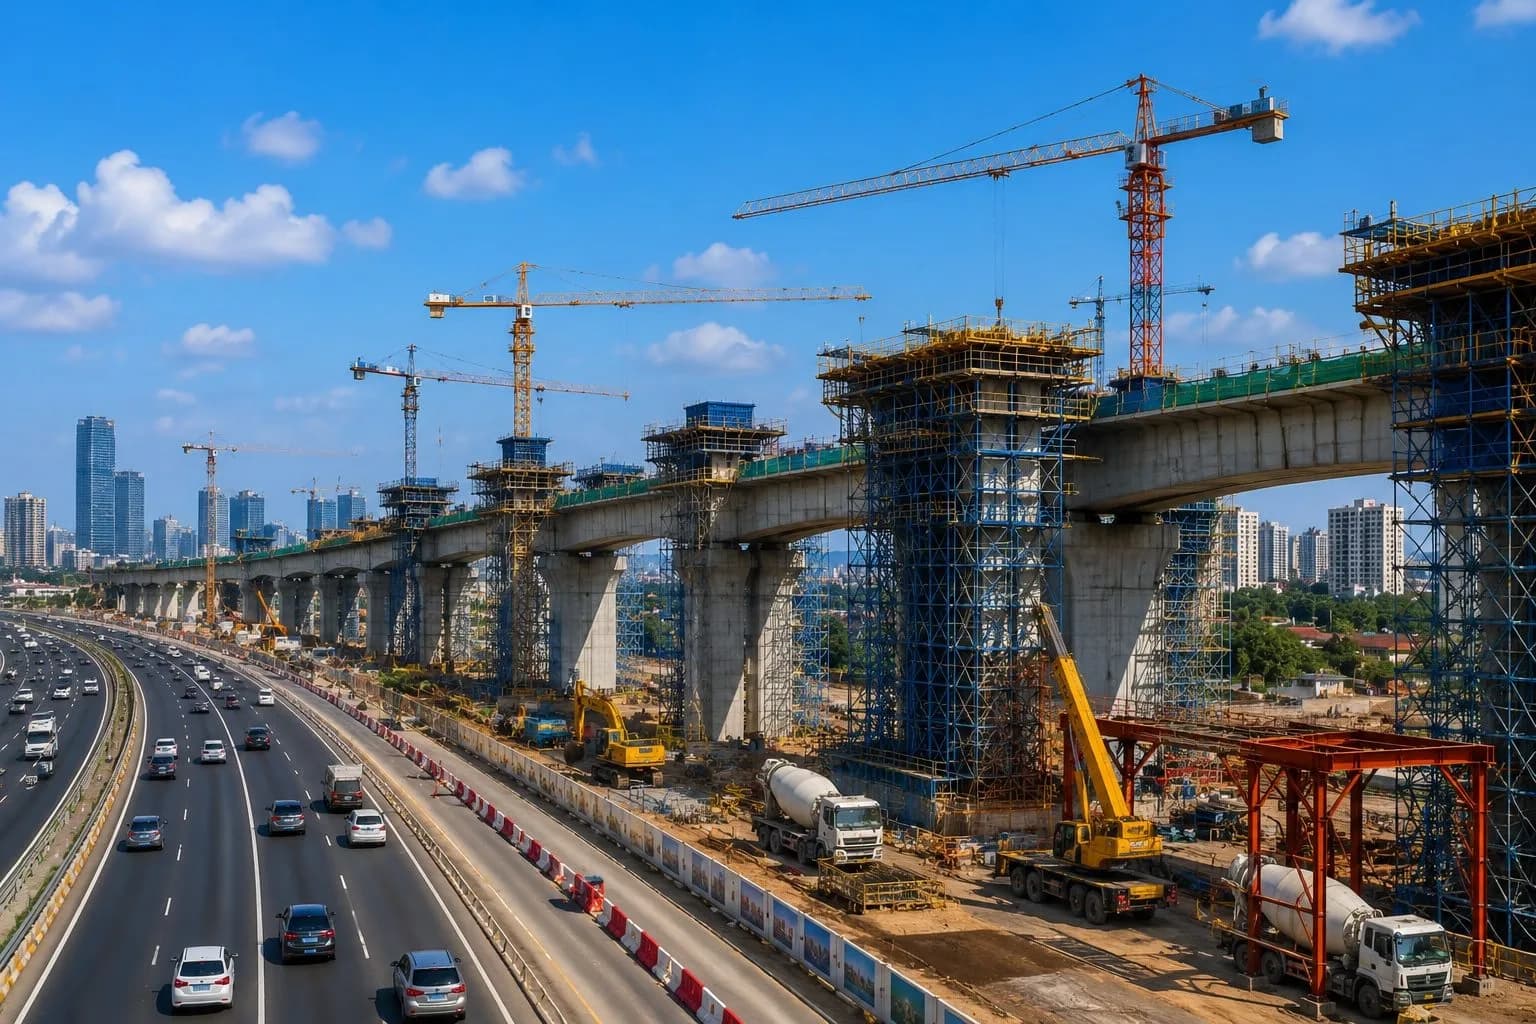
Chinese firms continue to dominate Africa’s infrastructure market through low-cost financing and integrated project delivery. But India, the Gulf states and Turkey are joining the race, making the continent’s infrastructure increasingly competitive.
China may still be Africa’s biggest infrastructure builder, but its dominance is no longer uncontested. India, Turkey and the Gulf states are steadily expanding their footprint by leveraging finance, construction expertise and strategic partnerships, reshaping the continent’s infrastructure market.
The latest example comes from Kenya. Two years after the collapse of India’s Adani Group’s proposed modernisation of Nairobi’s Jomo Kenyatta International Airport, state-owned China Road and Bridge Corporation (CRBC) secured a US$1.2 billion contract to execute the project.
A similar trend has emerged in Kenya’s highway sector. After France’s Vinci exited a major road concession, CRBC, alongside another Chinese company, stepped in as a developer. The original concession had faced criticism over concerns that it transferred most of the financial risk to the Kenyan government.
These projects reinforce China’s deep roots in Africa. According to local reports, CRBC alone has secured infrastructure contracts worth nearly US$9.3 billion in Kenya.
China’s biggest advantage remains its ability to offer an integrated package. Chinese firms typically combine financing, engineering and construction and, in many cases, long-term operations under a single arrangement.
This bundled approach can significantly reduce project execution risks for African governments while easing upfront financing constraints.
Analysts say Western companies often struggle to match these offerings. Higher labour costs, stricter financing requirements and greater risk premiums can make European and American firms less competitive in large infrastructure bids.
Instead, many Western companies have shifted towards high-value consultancy, design and project management, where margins are higher and competition from Chinese firms remains less intense.
China also benefits from structural economic advantages. As a capital-surplus economy with relatively lower engineering costs, it can finance and build large projects at prices many competitors find difficult to match.
Yet the competitive landscape is changing.
Turkey and the Gulf states are increasingly winning projects once viewed as China’s domain.
Turkish engineering firm Yapi Merkezi has emerged as a major railway builder in East Africa. It has constructed sections of Tanzania’s railway linking Dar es Salaam with Dodoma. In Uganda, it replaced China Harbour Engineering as the lead contractor for the Standard Gauge Railway after prolonged delays in securing Chinese financing.
Turkey’s competitive edge lies in relatively lower labour costs, combined with growing access to project finance and expanding technical expertise.
The United Arab Emirates has adopted a different strategy. Leveraging abundant capital, Dubai-based DP World has built one of Africa’s largest port portfolios through long-term concessions.
Its projects include the expansion of Somaliland’s Port of Berbera into a regional logistics hub, the development of Senegal’s deep-water Ndayane Port and investments in Mozambique’s Port of Maputo to accommodate larger vessels.
Unlike traditional construction companies, Gulf firms increasingly combine infrastructure investment with logistics, port management, aviation and trade connectivity.
India’s infrastructure ambitions in Africa remain more selective than China’s but are steadily expanding.
The Adani Group’s unsuccessful airport proposal in Kenya highlighted India’s growing interest in African infrastructure. Although the project eventually reverted to a Chinese contractor, the bid reflected New Delhi’s willingness to compete for strategic transport assets.
Indian companies continue to enjoy goodwill across several African countries through development partnerships, capacity building and concessional financing. However, unlike China, India has yet to build a comparable ecosystem that seamlessly integrates financing, construction and long-term operations.
The old narrative of “China versus the West” is increasingly outdated.
Today’s competition is far more complex. Chinese state-owned enterprises, Turkish contractors, Gulf investors, Indian conglomerates, African pension funds and multilateral development institutions are all competing for influence.
Each brings a different strength. China offers scale and integrated financing. Turkey competes on engineering expertise and labour costs. Gulf states leverage financial muscle and logistics capabilities. India seeks opportunities through strategic partnerships and commercial investments.
For African governments, this wider pool of bidders increases bargaining power while reducing dependence on any single external partner. It also gives governments greater scope to negotiate better financing terms, technology transfer and local participation.
China remains the dominant infrastructure player on the continent. But Africa’s infrastructure market is no longer defined by one country alone.
It is evolving into a multipolar arena in which financing models, geopolitical influence and long-term strategic interests increasingly determine who builds the continent’s next generation of roads, ports, railways and airports.

Comments
No comments yet. Be the first to share your thoughts.