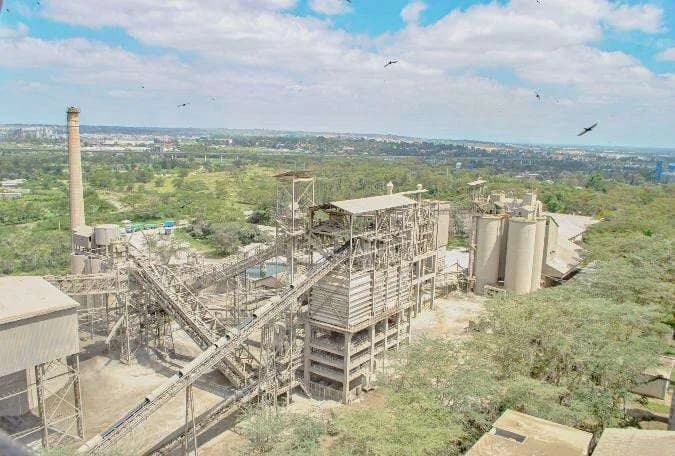
NAIROBI, Kenya, Oct 30 – East African Portland Cement Company’s (EAPCC) profit after tax fell 68.6 percent to Sh1.58 billion in the financial year ended June 2026, down from Sh5.02 billion recorded in the previous year, despite a strong recovery in cement production and sales volumes.
The decline was largely driven by a sharp reduction in fair value gains on investment properties and a swing in operating performance to a loss, reflecting rising production costs and expenses associated with the company’s business reorganization.
The cement manufacturer reported a 66.1 percent decline in profit before tax to Sh1.88 billion from Sh5.53 billion in the previous financial year, while earnings per share dropped to Sh17.55 from Sh55.82.
Fair value gains on investment properties fell 50.9 percent to Sh1.91 billion from Sh3.90 billion, reducing the contribution of non-operating income to the company’s overall profitability.
Operating performance also weakened, with the company recording an operating loss of Sh52.4 million compared to a profit of Sh1.64 billion a year earlier.
The decline came despite a 28.1 percent increase in revenue to Sh9.07 billion from Sh7.08 billion, supported by a 30 percent increase in cement production and a 29 percent rise in sales volumes during the period.
Gross profit improved 15.5 percent to Sh1.20 billion from Sh1.04 billion, although the gross margin narrowed by 1.1 percentage points as higher energy costs and logistics expenses pushed up production and distribution costs.
The company attributed the challenging operating environment to elevated inflation and supply chain disruptions arising from geopolitical tensions, which contributed to volatility in energy markets.
“The domestic cement market rebounded during the financial year resulting in higher product uptake although competition and price pressure persisted,” the company said in its financial results.
Cash generation also weakened, with net cash used in operating activities standing at Sh321.3 million compared to an inflow of Sh242.7 million in the previous year.
The company’s cash and cash equivalents declined 5.2 percent to Sh648.6 million from Sh683.8 million, despite total assets increasing 3.3 percent to Sh51.96 billion.
The board has not recommended a dividend for the year, opting to conserve cash for capacity expansion opportunities as it seeks to position the business to capture anticipated growth in cement demand.
EAPCC says it will prioritize restoring operating profitability through improved plant efficiencies and optimal sourcing, while pursuing capacity expansion to take advantage of infrastructure projects expected to sustain construction activity in the medium term.
Comments
No comments yet. Be the first to share your thoughts.