
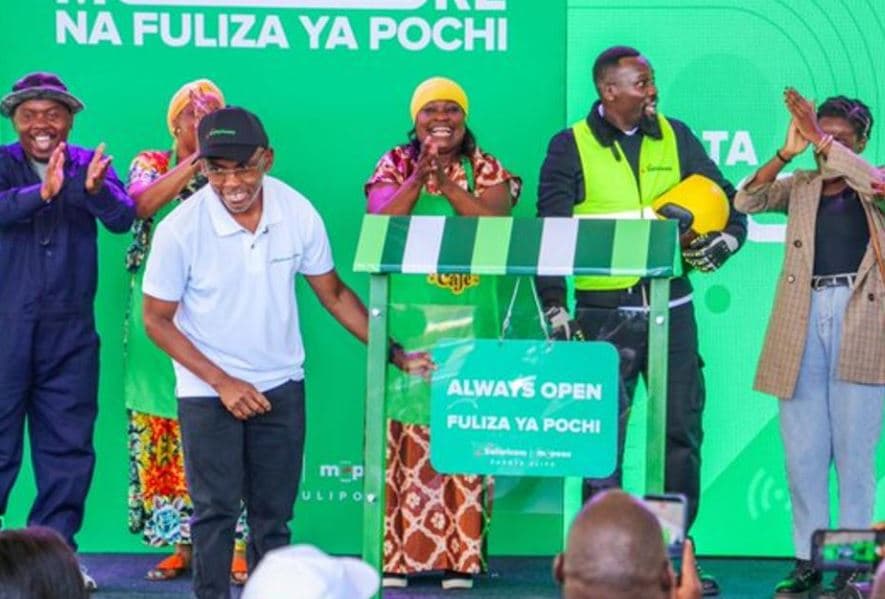
Small business owners in Kenya can now access short-term credit through Fuliza Ya Pochi, a new overdraft facility introduced by Safaricom to help eligible Pochi La Biashara merchants complete business transactions when their mobile money balances run low.
Launched on October 22, 2026, in Thika, the service targets traders who sometimes need to restock their shops, pay suppliers or settle bills before receiving their next payments. For a kiosk owner who needs to replenish cooking oil or a vegetable seller whose supplier expects payment immediately, a shortage of cash can mean losing valuable business time.
Fuliza Ya Pochi is designed to bridge such temporary gaps by allowing qualifying merchants to borrow within an assigned credit limit. However, like other digital credit products, it comes with repayment obligations that traders need to understand before using the facility.
How Fuliza Ya Pochi works
Fuliza Ya Pochi is an overdraft linked to a merchant’s Pochi La Biashara wallet. Instead of requiring a trader to apply for a separate loan every time money runs short, the facility allows eligible users to complete supported transactions using credit.
For example, if a trader has Ksh500 in their business wallet but needs to pay a supplier Ksh1,000, the overdraft may cover the Ksh500 shortfall, provided the transaction is eligible and the trader has sufficient available credit.
The borrowed amount becomes a debt that must be repaid. When customers subsequently send money to the merchant’s Pochi wallet, the funds are automatically used to reduce or clear the outstanding balance.
This means incoming sales may not be entirely available for restocking or paying other expenses until the overdraft has been settled.
Merchants can use the facility to pay suppliers, make Buy Goods purchases, send money and settle utility bills. The service is accessible through the Pochi Mini App on My OneApp or by dialling *334#.
Who qualifies and how credit limits are determined
Safaricom says merchants must have actively used Pochi La Biashara for more than six months to qualify. The company has indicated that more than one million merchants meet the initial eligibility requirements.
Having a Pochi account does not automatically guarantee access to credit. Merchants must meet the applicable conditions and receive an assigned limit.
The amount available to each trader depends on their business activity on the platform. Regular transactions can help demonstrate that an account is being used for business, although Safaricom has not publicly specified a universal credit limit for the new facility.
Traders should therefore check their individual limits through the official service menu rather than assume they can borrow a particular amount.
5 tips to follow before borrowing
1. Borrow only what your business needs
An overdraft can help a business overcome a temporary shortage, but it should not become the first option whenever money runs low. Before borrowing, establish the exact amount needed and what it will achieve.
Using credit to replenish fast-moving stock may help keep a shop running. Borrowing without a clear purpose, however, can leave a trader with debt and no additional income to show for it.
2. Check the fees before accepting credit
The amount borrowed is not necessarily the total amount that will need to be repaid. Digital credit facilities may include interest or other charges, depending on their terms.
Reports following the launch of Fuliza Ya Pochi have cited a one-off interest charge of one per cent and daily maintenance fees after a grace period. However, merchants should confirm the applicable charges, grace period and fee bands in the official terms presented to them before accepting the facility. They should not assume that charges for ordinary Fuliza automatically apply to this business overdraft.
3. Understand automatic repayments
Repayment is deducted automatically from subsequent payments received in the Pochi wallet. This can make repayment convenient, but it also means a trader may receive less usable money from daily sales while a debt remains outstanding.
For example, a shopkeeper expecting Ksh3,000 in customer payments should remember that some or all of that money may go towards clearing an overdraft rather than buying fresh stock.
4. Keep business cash flow in mind
Before borrowing, consider when the next sales are likely to come in and whether they will be enough to cover both the debt and other expenses.
A business with unpredictable sales may struggle if several days pass without enough incoming payments. Keeping a simple record of sales, stock purchases and outstanding credit can help traders avoid borrowing more than they can comfortably repay.
5. Read the terms and monitor your balance
Before opting in, check the credit limit, charges, repayment deadline and consequences of late payment. Merchants should also monitor their outstanding balances instead of assuming that small automatic deductions have cleared the debt.
Late repayment can affect access to future credit and may carry other consequences under the lender’s terms. If anything is unclear, seek clarification through Safaricom’s official customer support channels before proceeding.
Comments
No comments yet. Be the first to share your thoughts.