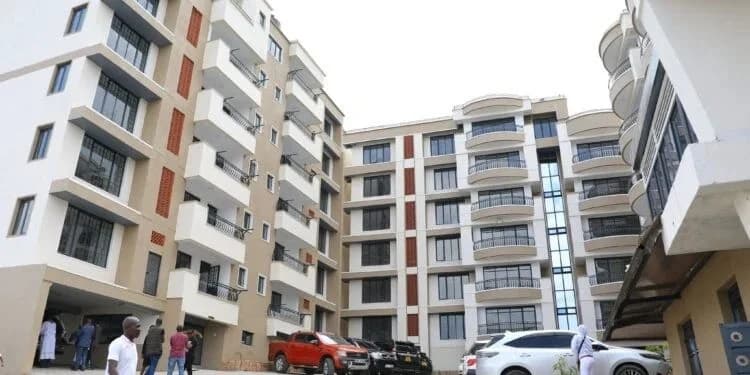
Mortgage interest rates in Kenya declined from 15.2 percent in 2024 to 13.5 percent in 2025, according to the Central Bank of Kenya’s (CBK) Residential Mortgages Market Survey 2025.
Despite the decline, the number of residential mortgage accounts stood at only 30,762 as of December 2025, the report shows.
“The interest rates for mortgage loans in 2025 ranged from 7.5 percent to 19.6 percent, compared to 8.2 percent to 20.4 percent in 2024. The average interest rate on mortgages was 13.5 percent in 2025, as compared to 15.2 percent in 2024,” the report cited.
Low Incomes and High Property Prices
The CBK report identifies low income levels as the biggest obstacle to growth in Kenya’s mortgage market, with banks citing limited household disposable income as a major constraint.
Many households therefore struggle to meet the monthly repayments required for mortgage financing.
Additionally, CBK highlights high property and land prices as another major challenge. The average mortgage loan size increased from KSh9 million in 2024 to KSh10 million in 2025.
“Based on the above ranking of mortgage market constraints, banks identified a low level of income, high cost of property purchase, and limited access to affordable long-term finance as the major impediments to the growth of their mortgage portfolios,” CBK said.
Additional Costs and Lending Requirements
The CBK survey notes that home buyers face additional expenses such as legal fees, valuation charges and stamp duty, which increase the overall cost of purchasing property.
Commercial banks also apply various lending requirements when assessing mortgage applications, including credit history, employment stability, debt-to-income ratios and the borrower’s ability to meet monthly repayments.
“Borrower’s character based on the credit history and Credit scores.” “Credit Rating of the borrower to ascertain credit soundness.”
Property registration and land titling challenges, together with lengthy legal charge processes, are also identified as factors that can delay mortgage transactions.
The report further lists limited access to long-term funding for lenders as a structural constraint affecting the mortgage market.
The survey also identifies limited consumer knowledge and awareness of mortgage products as a factor affecting mortgage uptake.
CBK Names Sectors Driving Kenya’s Bad Loans
Loans to landlords, shopkeepers and salaried workers made up a large share of Kenya’s non-performing loans (NPLs) in 2025, according to CBK.
The CBK report shows that the Personal and Household, Trade, Real Estate and Manufacturing sectors accounted for 72.1% of all gross loans in the banking sector as of December 2025.
The same four sectors also accounted for 72.6% of the total value of non-performing loans.
Personal and Household loans include credit given to salaried workers and other individuals, while Trade covers shopkeepers, retailers and wholesalers. Real Estate includes property developers and many landlords.
“The largest proportion of the banking industry’s gross loans and advances were channeled to the Personal and Household, Trade, Manufacturing and Real Estate sectors,” the report stated.
Follow our WhatsApp Channel and X Account for real-time news updates.
Comments
No comments yet. Be the first to share your thoughts.