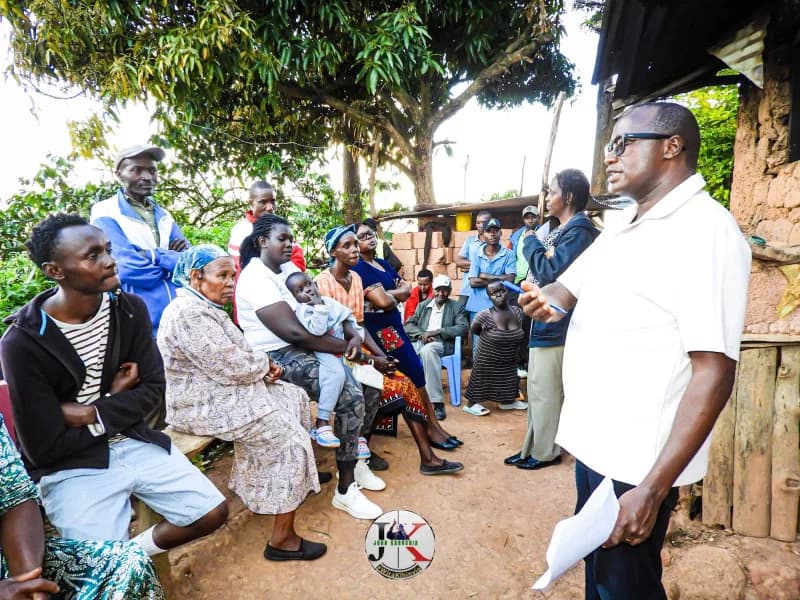
Mukurwe-ini MP John Kaguchia addressing residents of Thangathi in his constituency on October 27, 2026/ ALICE WAITHERA

Mukurwe-ini MP John Kaguchia wants students protected from high loan interest rates and unaffordable repayments under proposed reforms to tertiary education funding.
The lawmaker has proposed capping student loan interest rates at four per cent and linking repayments to graduates’ earnings to prevent borrowers from accumulating debts they cannot afford to pay.
In his submissions to the National Assembly’s Committee on Education on the Tertiary Education, Placement and Funding Bill, 2026, the MP backed the proposed reforms but called for amendments to guarantee scholarships for vulnerable learners and establish clear legal safeguards for student financing.
“I also support the commitment made by the President that every student who qualifies and is placed in a university or college will receive full funding,” Kaguchia said in submissions dated October 12.
He, however, warned that the proposed legislation does not adequately protect students from the risk of accumulating excessive debt because it leaves key funding terms, including scholarship allocations, interest rates and repayment thresholds, insufficiently defined.
“Unless those terms are fixed by Parliament, full funding risks becoming full debt for the poorest families,” he said.
The Bill proposes establishing a Tertiary Education Funding Authority (TEFA) by consolidating key functions currently performed by the Higher Education Loans Board (HELB), the Universities Fund and the TVET Funding Board.
The new authority would oversee student loans and scholarships, mobilise resources for tertiary education and manage loan recovery. The Bill also provides for means testing to determine the support students receive based on their household circumstances and other factors.
Kaguchia supports the consolidation but wants Parliament to establish minimum scholarship allocations for vulnerable and extremely needy students.
He proposes scholarships covering at least 62 per cent of programme costs for vulnerable learners and 70 per cent for extremely needy students, with no household contribution required from either category.
His recommendations draw on the Presidential Working Party on Education Reform, which proposed the scholarship allocations as part of efforts to ensure students from disadvantaged households can access higher education without shouldering excessive financial burdens.
The MP also wants the Bill amended to cap interest rates on student loans at four per cent annually, matching the current HELB rate.
He proposes that interest should not accrue while students are pursuing their studies or during approved periods of deferment.
Kaguchia cautioned that allowing the authority to set interest rates without a statutory ceiling could expose graduates to higher borrowing costs, particularly if TEFA raises money through commercial borrowing.
“The interest rate is therefore not a technical detail; it decides whether the loan can be repaid at all,” he said.
He cited the example of a four-year degree programme costing Sh729,600 in tuition and upkeep, arguing that a loan financed entirely through borrowing could grow to approximately Sh1.32 million at an 18 per cent interest rate by the time repayment begins, compared with about Sh837,800 at four per cent.
Kaguchia also wants the proposed requirement for graduates to begin paying their loans within one year of completing their studies replaced with an income-based system.
Under his proposal, repayment would begin only when a graduate's earnings exceed a prescribed threshold, with deductions calculated according to income. Repayments would be suspended during unemployment, further studies, incapacity or maternity leave.
The Bill proposes that employed graduates repay their loans through deductions from their earnings, capped at 25 per cent of their emoluments.
Kaguchia wants the deductions graduated according to income to protect low-paid workers from excessive deductions after statutory contributions.
He also wants the law to limit the combined interest and penalties recoverable on a loan to the outstanding principal amount when the loan falls into arrears, preventing debts from growing indefinitely.
Beyond student protection, Kaguchia has raised concerns about the financial implications of the proposed reforms, calling on the National Treasury to provide a detailed financial memorandum before the Bill proceeds to its second reading.
He cited funding gaps affecting HELB and university scholarships, alongside debts owed by public universities, arguing that Parliament needs clear estimates of government expenditure, borrowing requirements and the cost of subsidising student loans.
“The Bill is accompanied by no costing of the Exchequer contribution, the volume of borrowing TEFA is expected to undertake, the interest subsidy, or the repayment rate assumed,” he noted.
The MP also wants TEFA's borrowing subjected to annual limits approved by the National Assembly, with the authority required to disclose the amount borrowed, the sources and cost of funds, and any subsidies paid by the government.
He has proposed that students already enrolled in tertiary institutions retain the scholarship, loan and household contribution terms that applied when they joined, unless the new arrangements are more favourable.
Kaguchia further wants students and parents represented on TEFA's board, transparent recruitment of non-public servant members and annual reports detailing student support, debt levels, repayment rates and loan defaults.
He has also proposed provisions for loan write-offs in cases of death or permanent incapacity, as well as prolonged financial hardship under prescribed conditions.
“These amendments do not oppose the government's reform; they secure it,” Kaguchia said.
Comments
No comments yet. Be the first to share your thoughts.