
Anthropic is growing faster than almost any company its size, yet reports on its confidential draft IPO prospectus show that growth is arriving alongside financial commitments large enough to worry even bullish investors, with the public filing still to come and none of the figures confirmed by the company.
Start with revenue, which, according to Aljazeera, hit $16.3 billion in the first half of 2026, up from $1.1 billion a year earlier, and then reached $16.8 billion in the third quarter alone, meaning one three-month stretch now rivals the entire first half. Growth from one quarter to the next is cooling, though, so these numbers describe a fast-moving business rather than a guaranteed yearly pace.
The $80.7 billion loss for the same six months looks alarming, but roughly $72 billion of it is an accounting adjustment tied to how convertible notes are valued, which means it is not cash that left the company.
Strip it out and the loss shrinks to about $8.7 billion, still a real shortfall for a business that has not shown it can turn a profit, though a very different picture from the headline.
| Metric / Area | Reported Figure | Context & Analytical Takeaway |
| H1 2026 Revenue | $16.3B | Up ~15× year-over-year from $1.1B in H1 2025. |
| Q3 2026 Revenue | $16.8B | A single quarter now exceeds the entire previous half-year, though sequential growth rate is decelerating. |
| Reported Net Loss | $80.7B (H1 2026) | Headline distortion: ~$72B stems from non-cash accounting adjustments (convertible note revaluations). |
| Adjusted Cash Loss | ~$8.7B (H1 2026) | Real cash burn shortfall; the core operational deficit remains substantial. |
Running the models is also costly, with computing and infrastructure spending near $9 billion in that period, more than half of revenue.
The figure to keep an eye on is $518 billion, which, as reported by Reuters, is the minimum Anthropic has reportedly committed to pay Google, Amazon, Microsoft, and Broadcom-related equipment lessors over the next seven to ten years, with about 80% of it due whether or not the capacity gets used.
Measured against first-half revenue at a yearly pace, roughly $32.6 billion, that bill is close to 16 times larger, and while revenue should keep climbing and the payments are spread across many years, the company has to grow substantially just to keep up with what it has already signed.
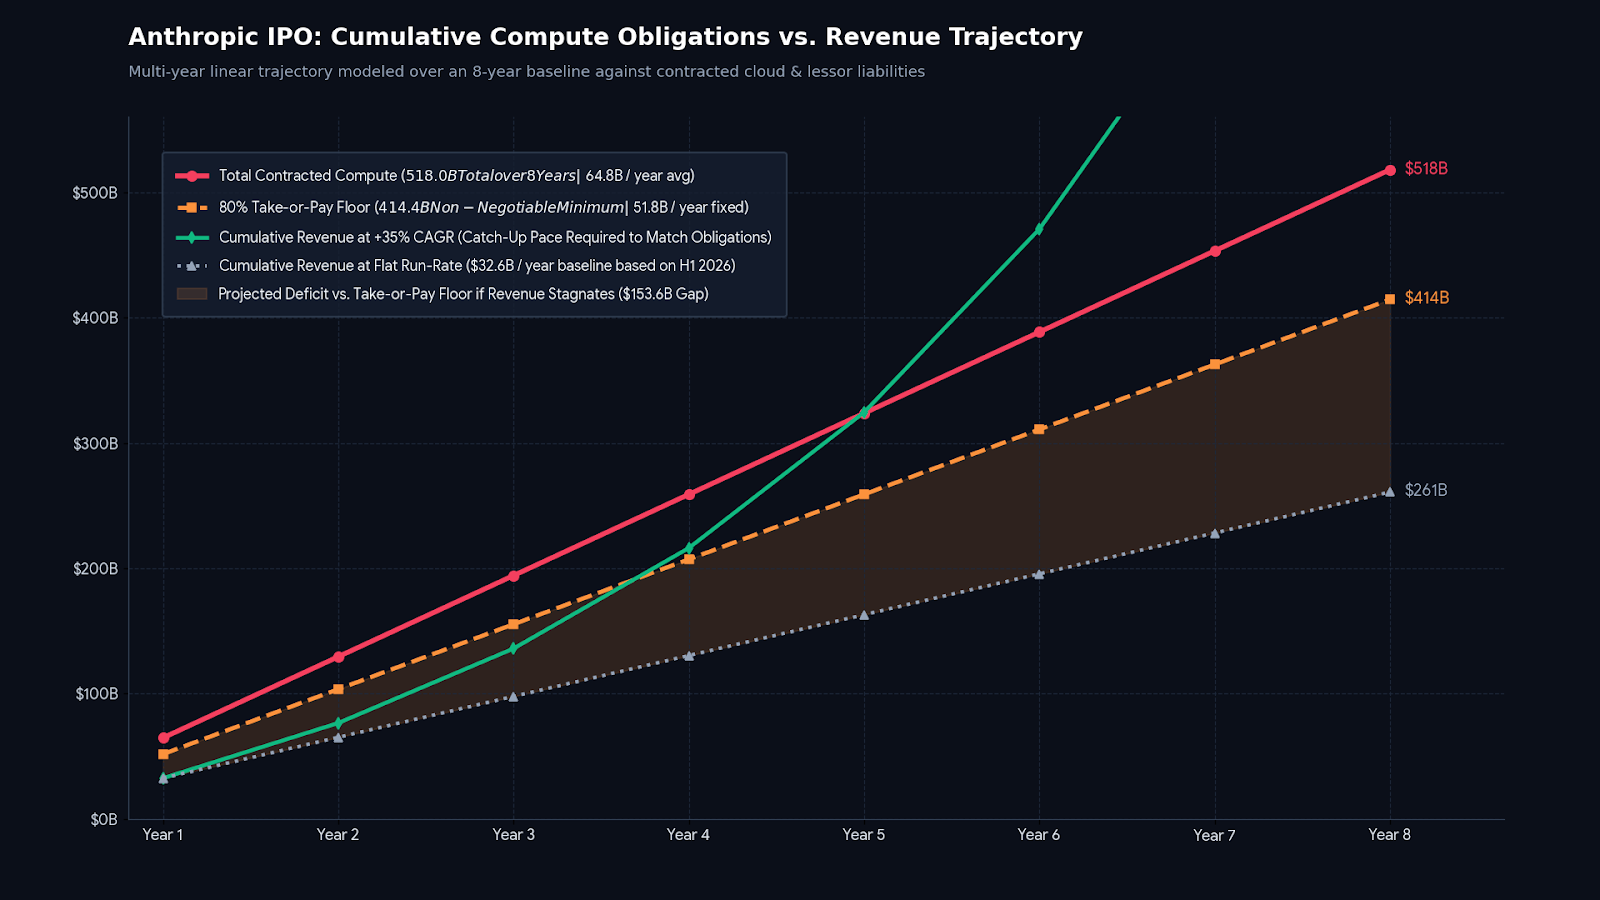
Valuation adds to the pressure, with earlier reports pointing to more than $2 trillion for the listing and some investors now talking about $1.5 trillion, which works out to roughly 46 to 61 times what Anthropic would earn in a year at its first-half pace, leaving little room for disappointment.
The hopeful reading is that Claude becomes a standard tool for companies and software developers, with products like Claude Code bringing in steady recurring revenue as computing gets more efficient.
The cautious reading is that rivals offer similar models more cheaply, forcing price cuts while the bills stay fixed, a risk sharpened by the fact that nearly a quarter of 2025 revenue came from just two customers, many of whom are not tied to long contracts, whereas Anthropic’s own obligations largely are.
Once the public filing arrives, the things worth checking are how much cash the business actually generates, how the commitments are scheduled year by year, and whether the cost of serving each customer is falling.
Comments
No comments yet. Be the first to share your thoughts.