
Standard Chartered Bank Kenya closed 2025 with a profit after tax of KES 12.4 billion, down 38% from the KES 20.1 billion it recorded in 2024, when the bank posted its strongest earnings to date.
The drop was driven by a combination of falling income across both interest and non-interest lines and a KES 2.6 billion charge to settle a pension dispute with former employees that had been in litigation for 16 years.
Total operating income fell 16.5% to KES 42.3 billion. Net interest income declined 13.1% to KES 28.9 billion, reflecting pressure on margins as the Central Bank of Kenya cut its benchmark rate to 9% by December 2025.
Non-interest income, which covers fees, commissions, and foreign exchange earnings, fell 23% to KES 13.4 billion. Total operating expenses rose 13.3% to KES 25.5 billion, largely on account of the pension settlement.
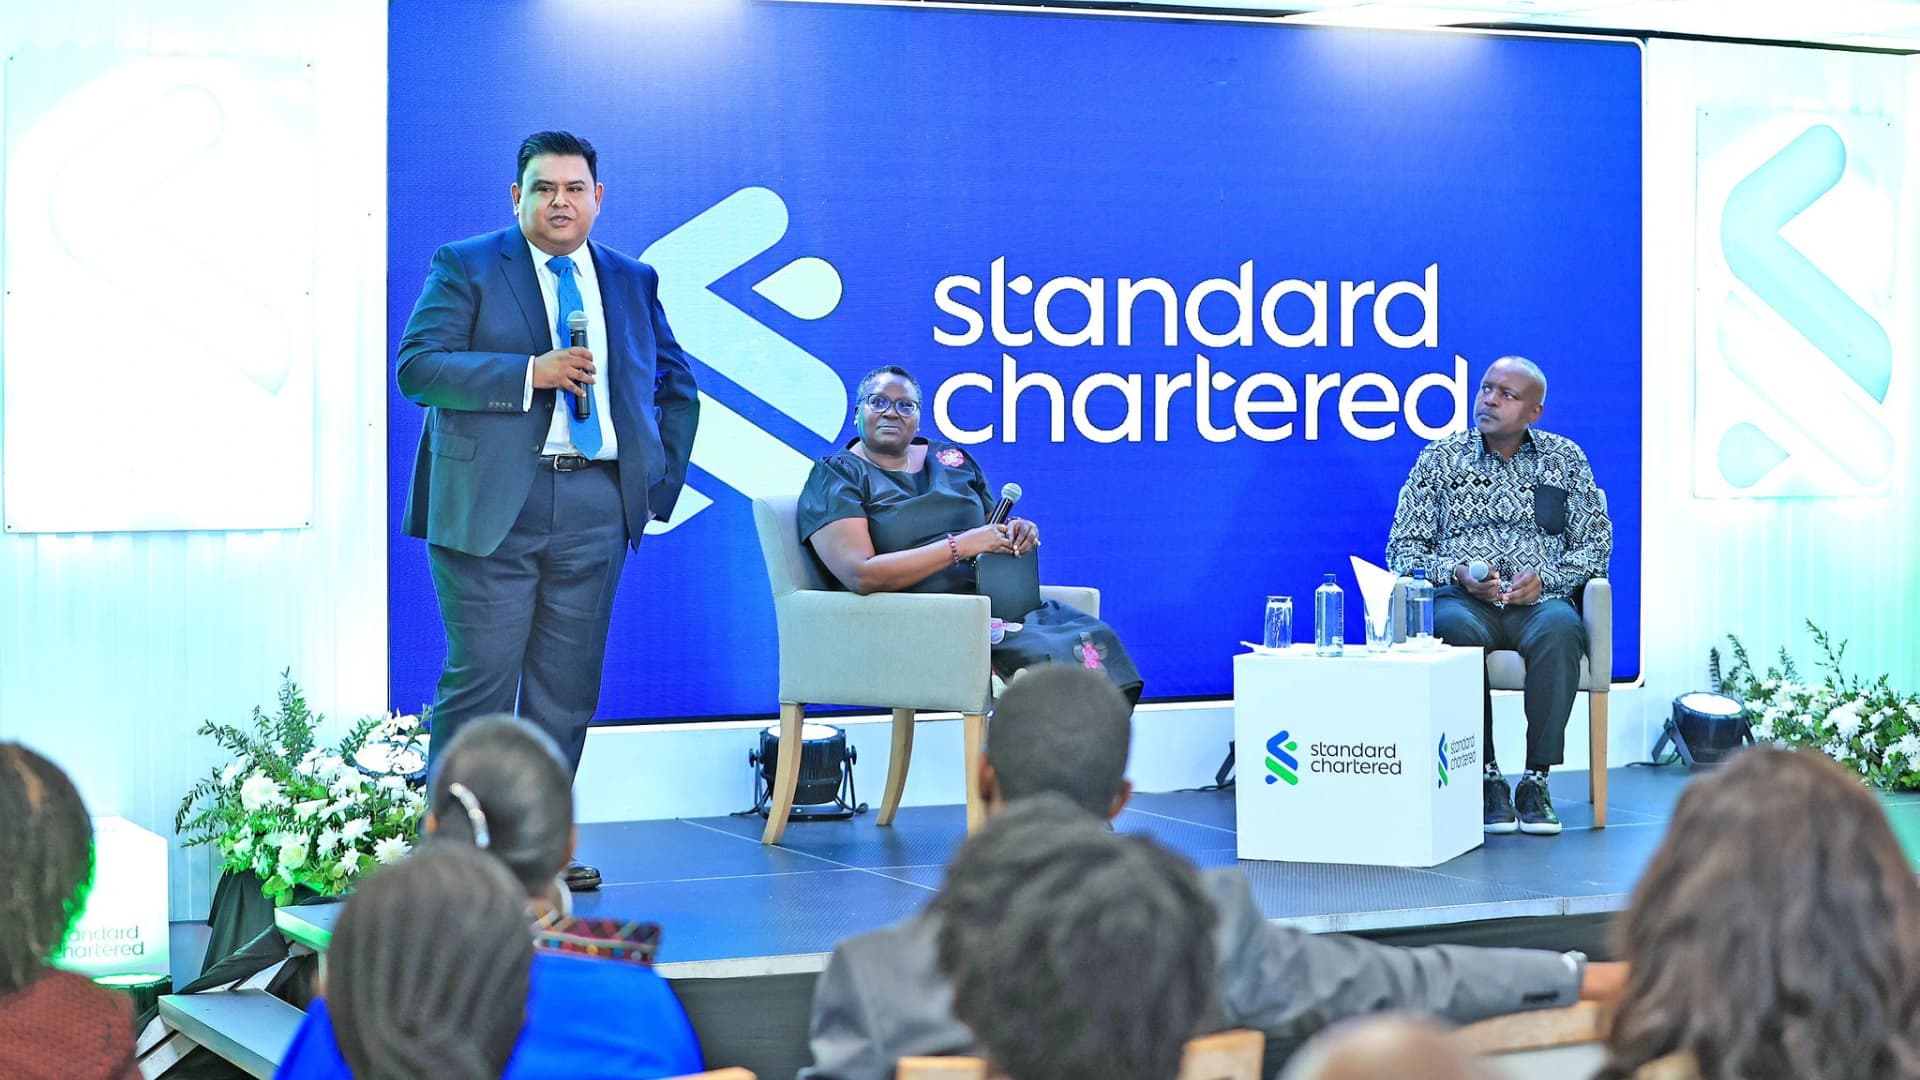
Speaking at the results presentation, CEO Kariuki Ngari pointed to growth in the bank’s wealth management business as a partial offset to the income decline.
Assets under management rose 29% to KES 302 billion, driven in part by net new money coming into the bank rather than funds shifted from existing accounts.
“Last year, that number grew 17%, and that was KES 70 billion of net new money,” he said. “So it’s an excellent vindication of not only the teams on the ground but also the products that we’re offering.”
The bank’s balance sheet also contracted. Total assets fell 5.5% to KES 363.5 billion, and customer deposits declined 4.1% to KES 283.5 billion. Net loans and advances to customers edged up 1.8% to KES 154.3 billion.
Asset quality improved. Gross non-performing loans fell 26.5% to KES 8.8 billion from KES 12 billion a year earlier, suggesting the bank worked through a portion of its distressed loan book.
Capital ratios also strengthened, with core capital to risk-weighted assets rising to 20.36% from 19.48%, well above the regulatory minimum.
Despite the earnings decline, the board approved a total dividend of KES 31 per share, down 31% from the KES 45 paid in 2024 but representing a 95% payout ratio against earnings per share of KES 32.47.
The total distribution amounts to KES 11.7 billion, the bulk of which flows to Standard Chartered PLC, which holds a 73.89% stake in the Kenyan subsidiary.
The results close a chapter for Ngari, who retires on April 16 after seven years at the helm. His successor, Birju Sanghrajka, currently Head of Corporate and Investment Banking, takes over as the bank navigates a lower-rate environment and works to recover income growth.
| Metric | FY 2025 (KES ‘000) | FY 2024 (KES ‘000) | Change |
| Profit After Tax | 12,436,571 | 20,060,587 | -38.0% |
| Total Operating Income | 42,301,736 | 50,677,085 | -16.5% |
| Net Interest Income | 28,891,842 | 33,265,303 | -13.1% |
| Non-Interest Income | 13,409,894 | 17,411,782 | -23.0% |
| Total Operating Expenses | 25,465,042 | 22,468,849 | +13.3% |
| Earnings Per Share (KES) | 32.47 | 52.65 | -38.3% |
| Dividend Per Share (KES) | 31.00 | 45.00 | -31.0% |
| Total Assets | 363,491,556 | 384,574,089 | -5.5% |
| Customer Deposits | 283,451,830 | 295,690,089 | -4.1% |
| Gross Non-Performing Loans | 8,834,664 | 12,018,504 | -26.5% |
| Core Capital / Risk-Weighted Assets | 20.36% | 19.48% | +0.88 pp |
| Total Capital / Risk-Weighted Assets | 20.41% | 19.55% | +0.86 pp |
| Liquidity Ratio | 64.40% | 67.59% | -3.19 pp |
The transition to Sanghrajka signals where Standard Chartered Kenya sees its growth runway. CIB and wealth management have been the two businesses holding up best against the income headwinds of the past year, with assets under management growing 29% and net new money into the affluent business rising 17%.
A leadership appointment from within CIB suggests the bank intends to lean into both.
Kenya’s rate cycle is in decline, which compresses net interest margins but tends to stimulate corporate borrowing and capital markets activity, areas where CIB earns.
The affluent segment, meanwhile, is less sensitive to rate moves and more dependent on product depth and client retention, both of which the bank has been quietly building.
The 2025 results, stripped of the pension one-off, still show a bank whose core revenues are contracting. Reversing that trend, rather than simply managing the decline, will be the first test of the incoming leadership.
Comments
No comments yet. Be the first to share your thoughts.