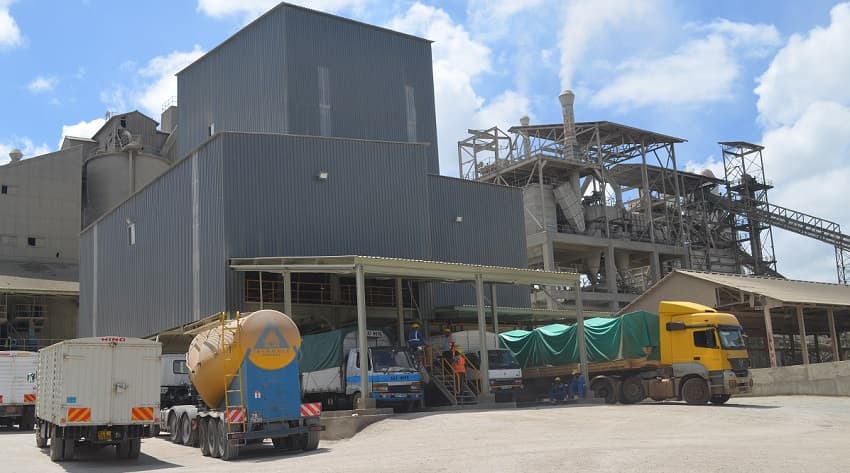
East African Portland Cement(EAPC) closed the 2026 financial year ended 30th June 2026 with stronger production and sales volumes, but profitability came under pressure.
Financial Performance of EAPC (KSh)
– Revenue: KSh 9.07billion, up 28.1%
– Gross Profit: KSh 1.20billion, up 15.5%
– Operating Result: KSh 52.4million loss, against a KSh 1.64billion profit in 2025
– Fair Value Gains: KSh 1.91billion, down 50.9%
– Profit Before Tax: KSh 1.88billion, down 66.1%
– Profit After Tax: KSh 1.58billion, down 68.6%
– EPS: KSh 17.55, down 68.6%
EAPC Balance Sheet & Cash Flow
– Total Assets: KSh 51.96billion, up 3.3%
– Total Equity: KSh 34.01billion, up 4.9%
– Cash Balance: KSh 648.6million, down 5.2%
– Operating Cash Flow: KSh 321.3million outflow, compared with a KSh 242.7million inflow in 2025
EAPC Operational Performance
– Cement production increased by 30%.
– Cement sales volumes grew by 29%.
Key Takeaway:
EAPC expanded production and sales, translating into stronger revenue. However, the sharp decline in earnings, the operating loss and the reversal in operating cash flow point to pressure beyond the top line. The reduction in fair value gains also contributed to the lower reported profit.
Outlook by the EAPC Board
Demand prospects premised on strong pipeline of infrastructure projects is expected to sustain construction activities in the medium term. Our priority is to restore operating profitability through plant efficiencies and optimal sourcing. EAPCC will remain focused on expanding capacity to capture anticipated demand growth, supported by strengthened governance structure for sustainable growth and returns to shareholders.
The Board said that in order to conserve cash for capacity expansion opportunities on order to capture the growing demand, it is not recommending a dividend for the year ended 30th June, 2026.
Comments
No comments yet. Be the first to share your thoughts.