
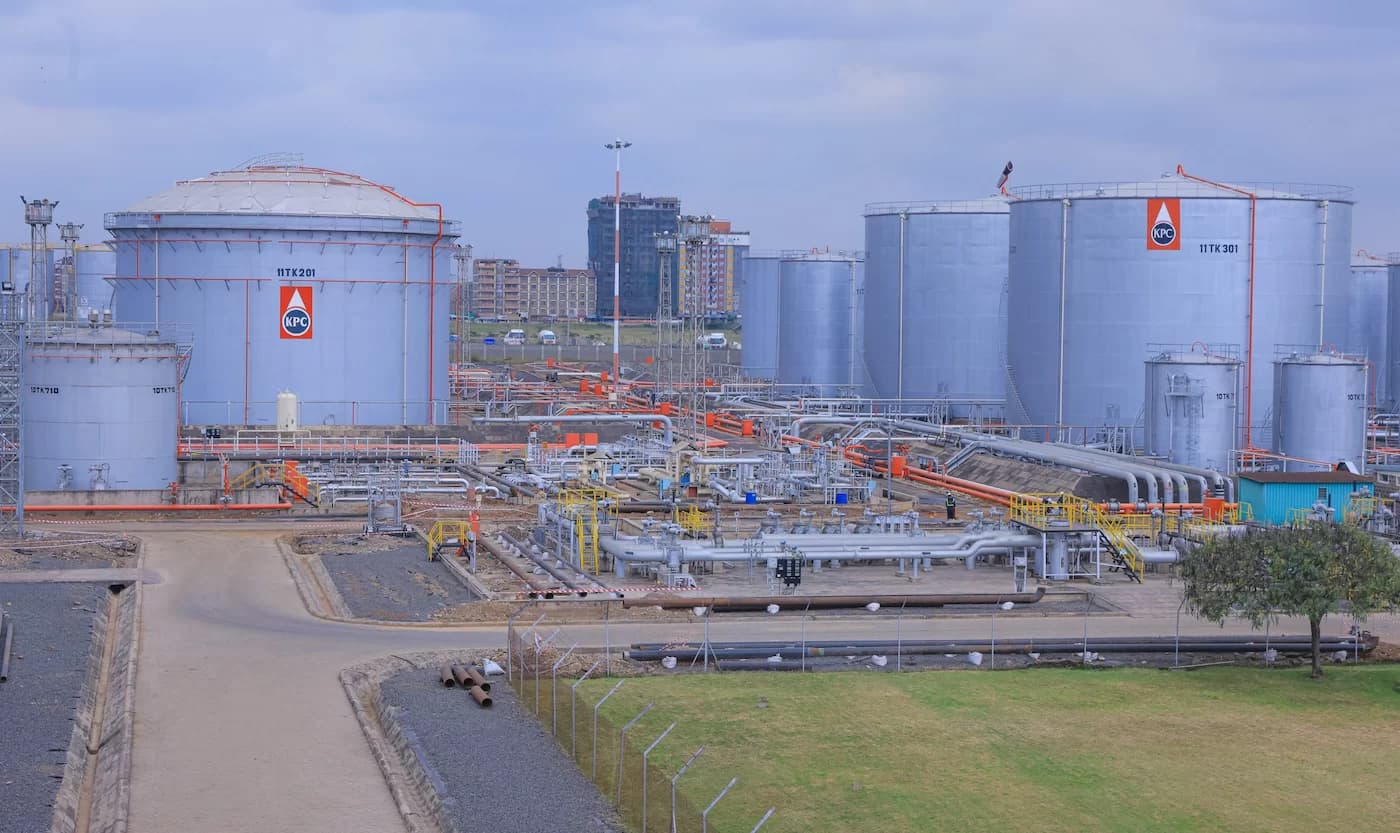
The KPC (Kenya Pipeline Company)-Dangote Deal is more that Dangote owns in the pipeline company. It is what he brings to the table. The biggest strategic benefit, is the potential alignment between his planned Lamu refinery and Kenya Pipeline Company existing pipeline infrastructure. Rather than developing a refinery that competes with KPC’s distribution network, he now has a direct financial interest in the success of that network.
KPC goodies in the deal
There is an incentive to work together, although an actual supply or transportation agreement has not yet been publicly confirmed.
Secondly, Kenya Pipeline gains a shareholder with substantial experience in refining, energy infrastructure and large-scale industrial investment. If that translates into additional investment, expanded pipeline capacity and greater regional fuel-distribution volumes, it could create value for Kenya Pipeline and its shareholders.
And for now, Dangote also gets to collect dividends from the table.
Of course, owning 24.76% does not give him unilateral control, and strategic alignment does not eliminate commercial or governance risks.
As investors, we should look beyond the personality and examine the strategic logic of the transaction.
What incentives does it create? What new opportunities could emerge? How might those opportunities translate into revenue, earnings and dividends for Kenya Pipeline Company?
The sellers of the 25% stake in Kenya Pipeline Company (KPC) reportedly include state-backed pension funds and agencies such as NSSF, the Public Servants Pension Scheme, County Workers Pension Fund and UFAA, alongside pension schemes of Kenya Power, KPC and KPA.
Their combined shareholding has reportedly fallen from 38.35% to below 15%, with Dangote emerging as KPC’s second-largest shareholder after the government. In deals of this nature, both sides have strategic interests.
Dangote could not just invest in Kenya Pipeline unless he was actually a shareholder. The government also needed to mitigate the risk of Dangote building a pipeline that would compete with KPC. But, of course, we all know kickbacks are always there—not necessarily in the form of cash.
Nonetheless, Dangote’s investment in Kenya Pipeline is a positive. At least now we know he won’t be competing with KPC.
“As investors, emotions arising from political affiliations, personal beliefs, culture and other biases have to be checked. They should not dictate our investment decisions. The biggest question is: How do I benefit from this deal, and how do I position myself to benefit?” said CFA Dedan Maina.
Comments
No comments yet. Be the first to share your thoughts.