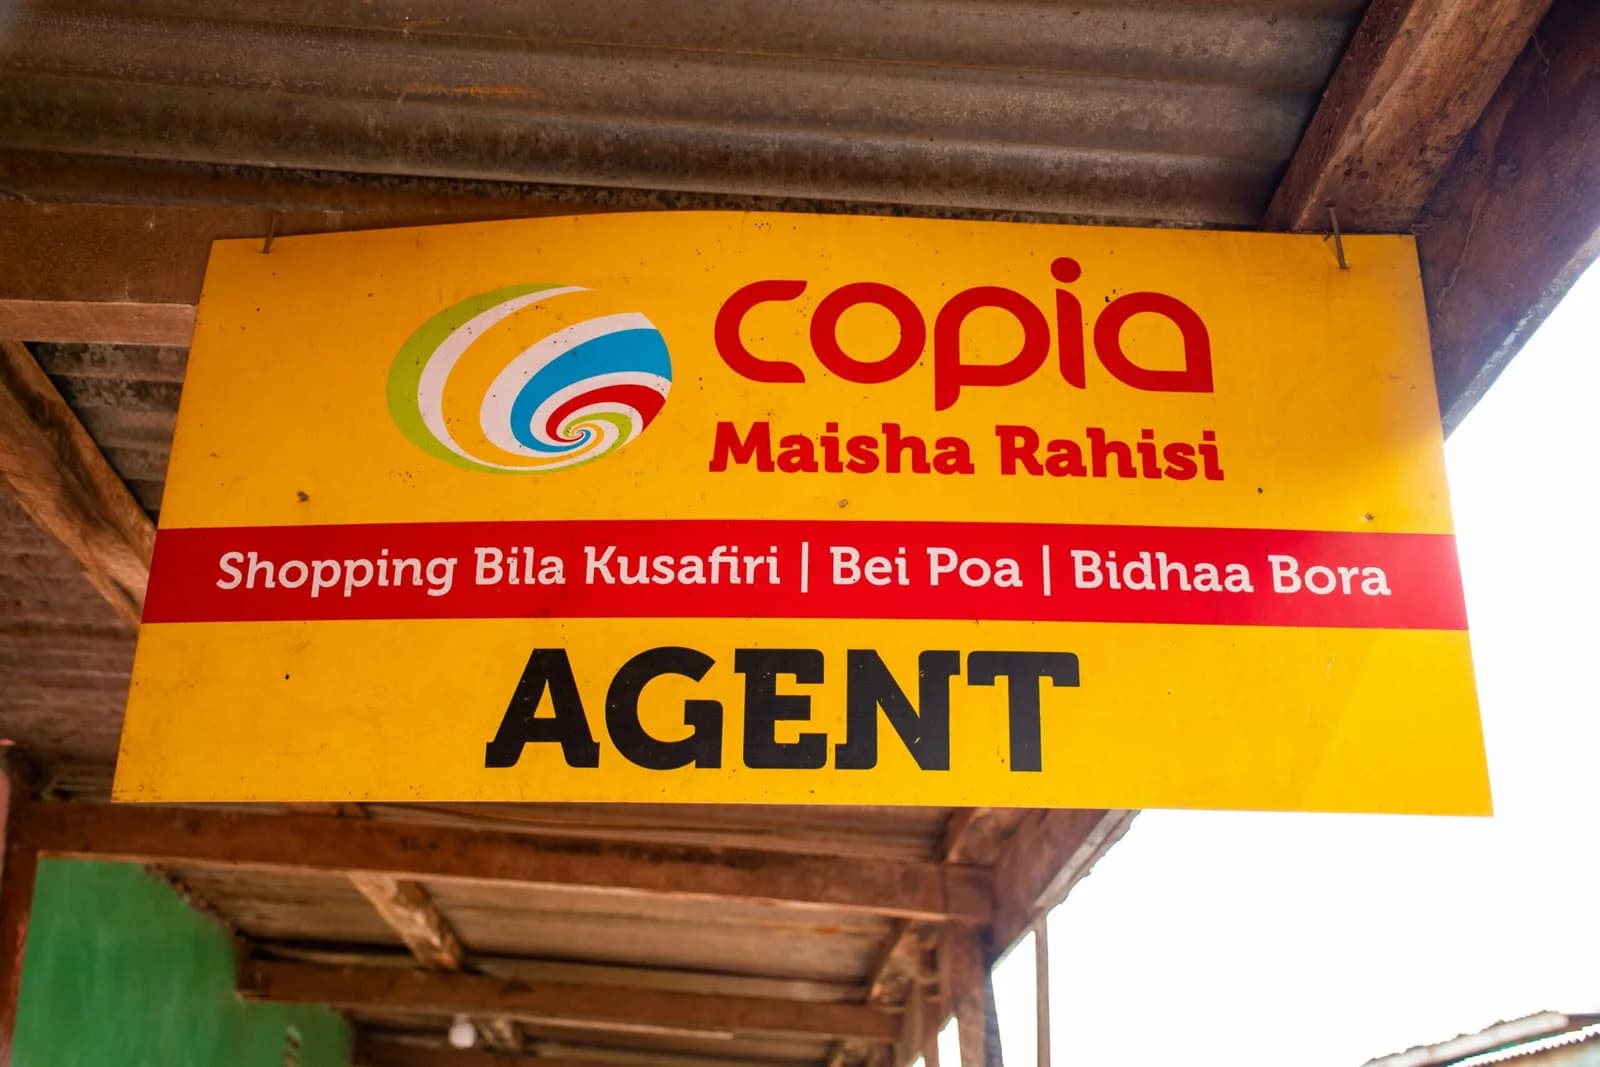
Copia Kenya Limited, the e-commerce company that sold everyday goods to rural Kenyans through local shop agents, is being wound up. On 17th September 2026, Justice Rhoda Rutto of the High Court in Nairobi ordered it into liquidation, the process in which someone is appointed to sell what a company still owns and pay its debts in a fixed order. She named Julius Mumo Ngonga and Anthony Makenzi Muthusi of KPMG Advisory Services Limited as the joint liquidators.
The same two have run it since May 2024, when it entered administration, a court-supervised period that gives a failing company time to be rescued or sold off. After two years the court found no realistic prospect of a rescue and said carrying on would only add delay and expense for creditors.
The question for Copia’s creditors is whether anything is left to share. The administrators’ creditors’ report, dated 12th March 2026, put Copia’s realisable assets, meaning what it can expect to sell, at about KES 206.6 million as at 28th February 2026, against about KES 169.5 million in creditors’ claims and administration costs. On those two figures alone, about KES 37 million would be left over. The administrators told the court otherwise: that Copia’s liabilities exceed its assets and that, even in the best case, only preferential creditors, a class that includes employees, may receive a distribution. The ruling does not reconcile the two.
Secured creditors, who hold collateral such as a bank’s charge over property, are paid first, then preferential creditors, then unsecured ones, and investors come last. Two unsecured suppliers went to court. Tuffsteel Limited says it is owed KES 13,312,133. Jastan Traders Limited, a delivery contractor, says it is owed KES 793,022 as at 25th May 2024, before interest.
The investors are further back still. About USD 123 million, or about KES 16 billion at KES 129.7 to the dollar on 30th September 2026, went into the parent company, Copia Global, from backers including Enza Capital, Lightrock, Goodwell Investments and the US International Development Finance Corporation. That total has moved: we put it at USD 107 million, or about KES 13.9 billion at the same rate, in 2024, so treat USD 123 million as the latest count, not an audited one. The parent, Copia Global, Inc., filed for Chapter 7, the US form of liquidation, in Delaware on 23rd May 2024. That case closed on 5th April 2025.
Neither Tuffsteel nor Jastan opposed liquidation itself. Both objected to how it would be done. Tuffsteel asked for orders preserving Copia’s assets, an inventory within 14 days and an independent forensic audit, an outside investigation of the books, covering the three years before administration. Jastan backed the application and questioned the reported sale of Copia’s brand, intellectual property and transactional data to a company called Copia Holdings Limited, and asked whether it was at arm’s length and for fair value. Both also objected to the administrators becoming liquidators, because they would then be reviewing their own work.
The judge dismissed Tuffsteel’s application. She found the concerns largely precautionary: no specific asset had been shown to be hidden or undervalued, and no independent valuation put the sale below market value. She wrote that “the Court cannot infer impropriety solely from the fact of the transaction”. She also found no law that stops an administrator from becoming the liquidator of the same company. Each side bears its own costs.
The ruling does not say what Copia Holdings Limited paid, who owns it or when the sale closed. It refers to a disclosed consideration for the sale but does not print it. It puts no figure on what former employees are owed, although it refers to preferential employee claims.
The audit the creditors wanted may still happen, but not through the court. Liquidators, not administrators, hold the powers to challenge transactions at an undervalue, payments that favoured one creditor over others, and misconduct by directors, which the administrators themselves argued only start once liquidation does. Ngonga and Muthusi now hold those powers over a period they ran. That is lawful, and the judge saw no sign of misconduct. She left creditors free to come back with evidence. It does mean scrutiny of the administration now depends on creditors bringing that evidence to court, because the outside review they asked for was refused.
Copia sold to rural and peri-urban shoppers. A customer ordered by USSD (a menu opened by dialling a short code), by phone, from a printed catalogue or in an app, and a local shop agent took delivery. By Copia’s own count in December 2023 it had more than 50,000 agents. The asset list the administrators put up for sale in August 2024 cited an agent network of about 30,000 stores and a customer base of about two million. Copia had put its Uganda venture on hold in April 2023, which we covered at the time, and by the time of that sale its parent had been unable to attract capital on terms all its existing investors would accept. The 1,060 jobs ended on 7th June 2024.
Jumia, which still sells in Kenya, has a different mix. Across its markets, 75% of the packages it shipped in the second quarter of 2026 went to pickup stations where customers collect them, up from 71% a year earlier. Orders from what Jumia calls upcountry regions made up 61% of the total, and a higher share of sales came from third-party sellers, on which Jumia earns a commission instead of booking the sale itself. The release does not split those figures for Kenya. Jumia is also still losing money. Its adjusted EBITDA loss, a profit measure that leaves out interest, tax, depreciation and share-based pay, was USD 8.7 million, or about KES 1.1 billion, in the quarter. On 12th August 2026 it announced a USD 50 million, or about KES 6.5 billion, capital raise anchored by the International Finance Corporation, and it targets breakeven on that measure in the fourth quarter of 2026.
Our reading is that Jumia’s figures show shoppers outside the biggest cities will order online when the parcel goes to a nearby pickup point and more of the sales come from third-party sellers. They do not yet show that it pays. Copia went after the same shopper through shop agents and, with about USD 123 million raised, still did not reach a business that could run without another round. The ruling does not try to explain why, because nobody asked it to.
What the court settled is a procedure. For suppliers and former employees the next things to watch are the directors’ statement of affairs and the liquidators’ reports to the court, which the administrators told the judge would follow.
Comments
No comments yet. Be the first to share your thoughts.