
For years, the story of Kenya’s stock market has been told through its glaring absences.
Too few new listings. Too many companies choosing private capital. Too little excitement beyond the familiar corporate and blue-chip names. But this narrative is -seemingly- beginning to change if activity at the Exchange recently is anything to go buy.
However, the real test of Kenya’s capital-market revival will not be how many companies ring the bell at the Nairobi Securities Exchange. It will be whether the market can become useful to a wider range of businesses and investors.
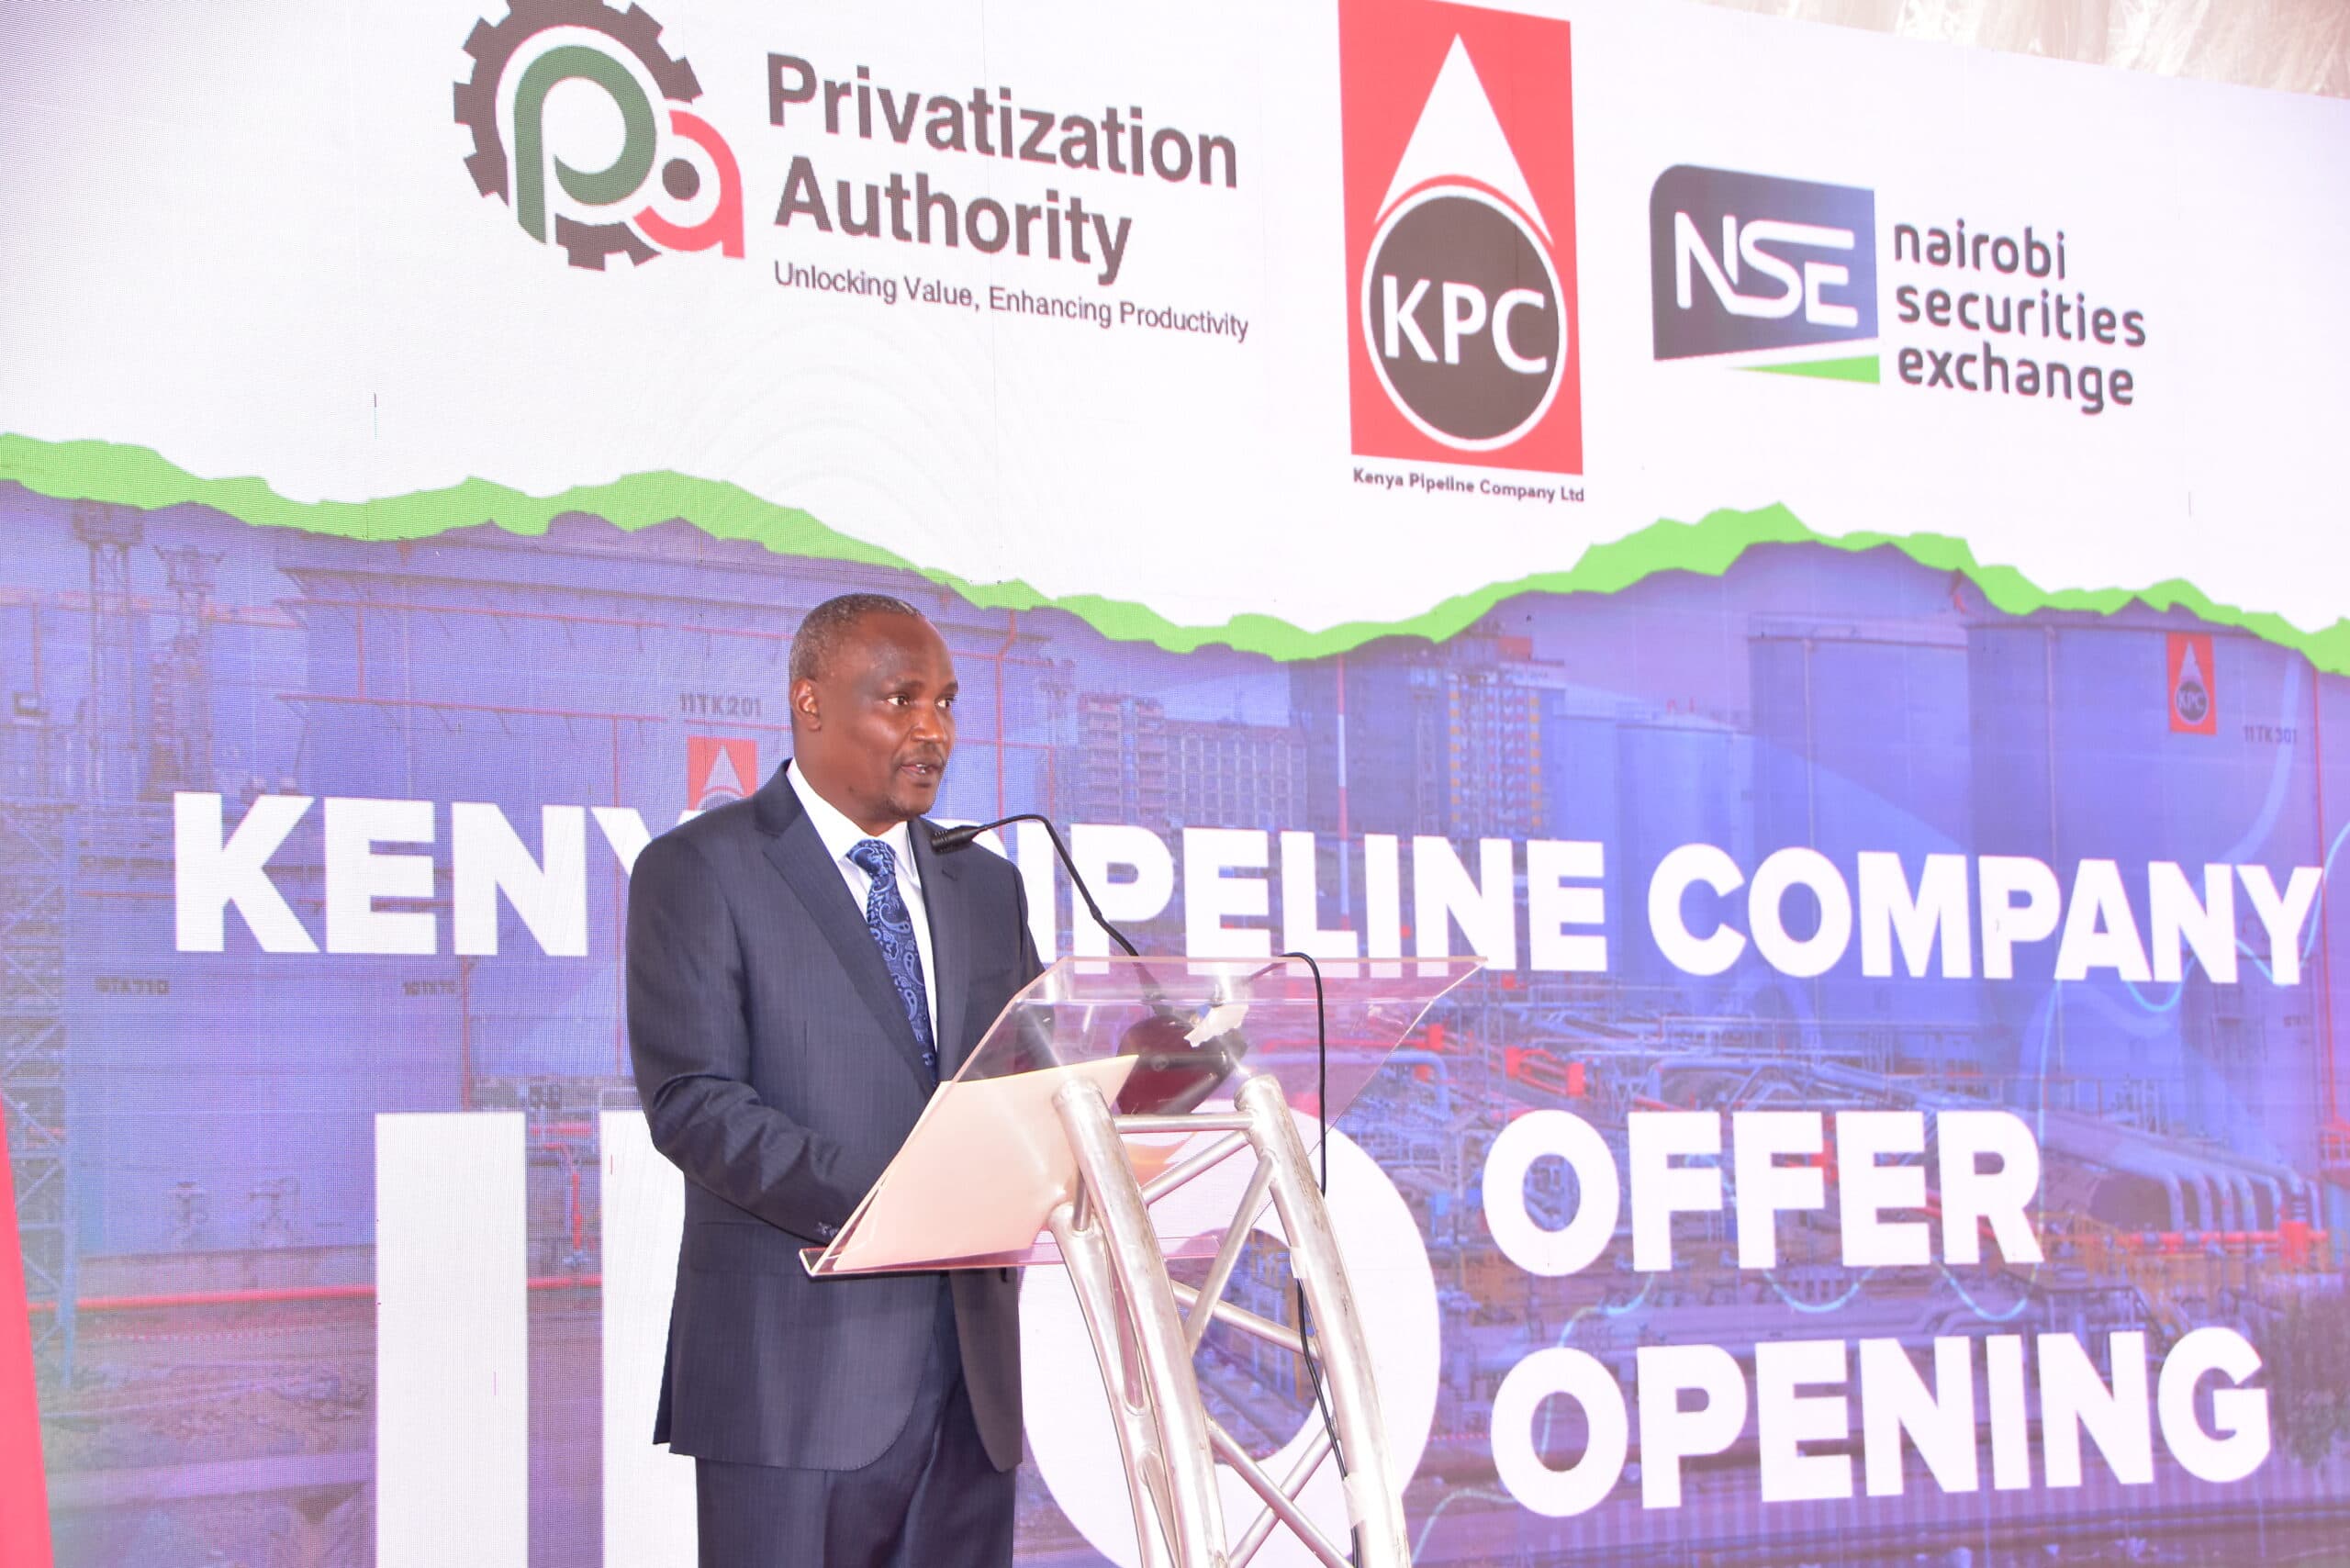
For instance, the Kenya Pipeline Company listing in March 2026 marked a significant moment. Its Ksh. 106.3 billion offer attracted applications exceeding the shares available, demonstrating substantial appetite for a large, recognisable Kenyan enterprise.
Quickmart’s October share offer on the other hand brings a different proposition: an established consumer business entering public ownership.
Meanwhile, the ALP Industrial Real Estate Investment Trust has demonstrated how the exchange can accommodate investment in income-producing industrial property.
These transactions are not interchangeable. That is precisely why they form a good analysis.
A mature capital market should do more than facilitate the occasional blockbuster initial public offering. It should connect different kinds of businesses with investors seeking different forms of exposure, liquidity and returns.
Consider the choices facing a growing Kenyan enterprise.
Bank borrowing can finance expansion, but repayment obligations may constrain investment. Private equity can bring capital and expertise, but investors eventually need an exit.
A conventional IPO offers broader ownership, although its disclosure requirements, preparation costs and valuation uncertainties can be demanding.
Other instruments, including real estate investment trusts, corporate bonds and special purpose acquisition companies, can offer different routes to public-market participation. But the big question remains – do businesses have enough credible options to select the one that best fits their circumstances?
There is also a distinction between raising capital and listing shares.
Quickmart’s offer, for example, involves the sale of existing shares by its shareholder. The proceeds do not go directly into the retailer’s balance sheet. Yet such transactions can still deepen the market by broadening ownership and creating a publicly traded investment opportunity.
That distinction is key because capital-market development cannot be measured solely by money raised for expansion. Liquidity, price discovery, investor participation and credible exits are also essential.
Kenya has considerable pools of domestic savings, including pension and institutional capital. Connecting those resources to productive enterprises requires more than a succession of high-profile offers. It requires a dependable pipeline of investable companies, appropriate structures and investor confidence.
A revived exchange must also protect investors through sound governance, transparent disclosures and realistic valuations because new listings that disappoint investors can weaken the very confidence the market is trying to rebuild.
The opportunity now is to turn renewed attention into lasting depth.
More IPOs for Kenya’s capital-markets success are good. But an exchange capable of supporting many different routes to investment, ownership and growth is even better.
By Leonard Mudachi
Comments
No comments yet. Be the first to share your thoughts.