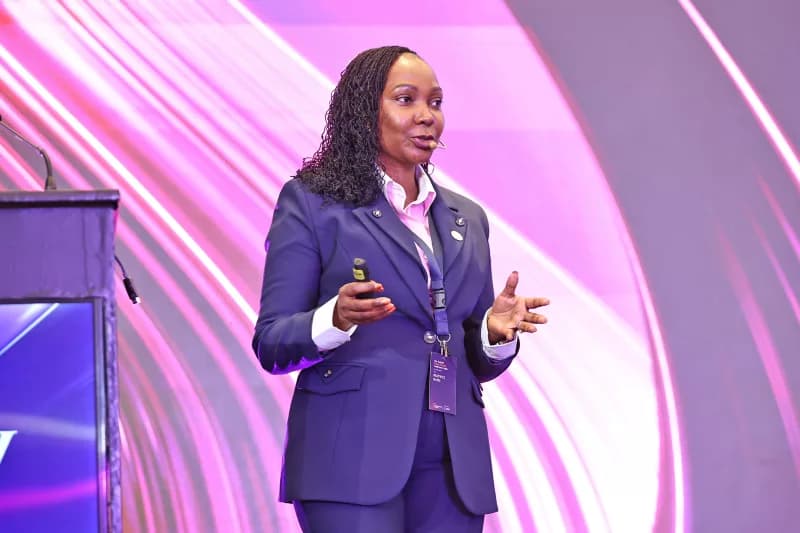
CPA Beatrice Njeri, Partner, Tax Compliance and Accounting at Tarra Agility Africa speaks during the recent Nairobi Private Wealth Conference, June 2026/ HANDOUT

THE frequency of tax-related disputes between Kenya Revenue Authority and businesses have over the years increased and are now a part of doing business in Kenya. According to a new study by Tarra Agility Africa, a Nairobi-based international tax, legal and accounting firm , the odds have shifted in favour of the revenue authority. An assessment of over 5,000 decided tax cases spanning a fifteen-year period and drawn from the Tax Appeal Tribunal and Kenya Courts, reveals that the taxman win rate is 52% compared to 36% in favour of taxpayers, with the rest being split. Today, the revenue authority is winning close to six in ten cases. And the reasons are surprisingly ordinary; missing paperwork, unproven claims, and missed deadlines.
Later this month, the firm is launching the Africa Tax Terminal, a platform that combines judicial precedence, legal and tax and accounting expertise, and cutting-edge technology that seeks to flag tax risks before they become tax bills.
The Star’s Martin Mwita spoke to CPA Beatrice Njeri, Partner, Tax Compliance and Accounting at Tarra Agility Africa on why firms are losing cases and the best way to go about compliance and avoiding prolonged litigations with the taxman.
What problem are you trying to solve?
During our practice at Tarra Agility, we realized that most companies conduct deep tax health checks as an annual ritual. These reports remain stuck at the board or senior management level and are rarely implemented by finance staff. Further, while many finance teams are aware of tax changes resulting from well publicized tax changes such as during the Budget period in June, tax changes from decided case law get less attention. This is a structural gap. Finance teams are busy running the business and cannot reasonably be expected to keep tabs with decided court cases.
Further, many tax cases remain unpublished and unavailable unless accessed through public court registries. Even when accessed, the sheer volume of these cases can be daunting even to the most enterprising finance team. In the same vein, the law changes all year round. Parliament passes the Finance Bill every June, the KRA issues notices throughout the year, while the Tax Appeals Tribunal and courts make determinations weekly.
Finance professionals also depend on fragmented tax training sessions offered across the year. These are not industry-specific, never encompass the entire finance team and, therefore, barely result in structured tax governance protocols implementable on an ongoing basis to secure the company against a KRA challenge. Often, by the time an auditor flags tax issues during the annual audit, interest and penalties have accumulated for months. The system is broken, either by default or design.
Tell us a bit about the 15-year analysis you conducted and how exactly it will assist taxpayers navigate this system you describe as broken.
We have mapped nearly 74,000 rules and tax principles applicable across tax heads such as withholding tax, customs, PAYE, Corporate Tax and VAT. They have been extracted from case law, statutes, KRA notices and Double Tax Agreements, and constitute the engine that answers client queries and performs on-demand tax health checks. We aim to facilitate businesses to advance from periodic reviews to continuous monitoring, powered by timely information on legal changes, and backed by our team’s professional advice.
What sectors did you find were more at risk of disputes?
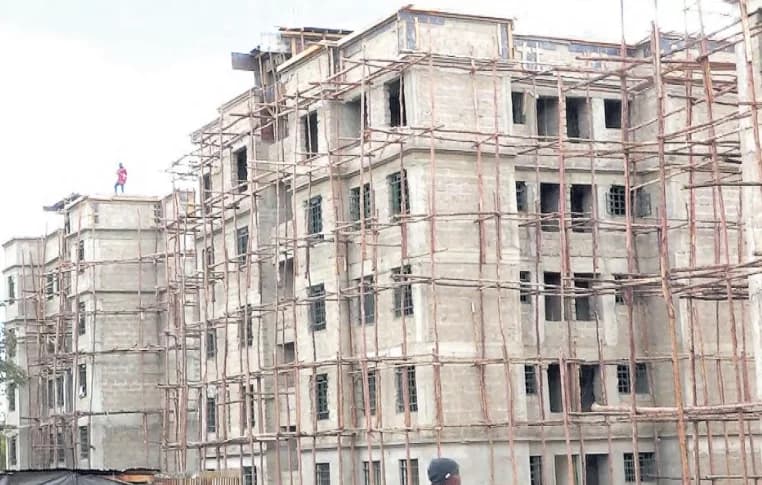
In the construction and real estate sectors, the taxman won 63 per cent of the cases, followed by retail and wholesale sectors where businesses involved lost 61 per cent of the time. The taxman has also enjoyed an over 50 per cent success rate in disputes involving professional services and consulting, transport and logistics, hospitality and leisure, as well as healthcare. Financial services is the one large sector where taxpayers won more decided cases. Further, taxpayers won most customs cases involving valuation and classification of imported goods into the Kenyan market. For PAYE controversies, the revenue authority and the taxpayer were evenly tied in terms of judicial success. The key lesson is that industry context significantly influences tax risk and litigation outcomes.
Regarding the decided matters, what were your findings regarding the reasons cases were lost or won in court?
Mostly, taxpayers who were unable to adequately articulate their position at the Tax Appeals Tribunal by providing corroborating evidence to support their position, found themselves saddled with a massive tax bill since the burden to disprove tax demands sits with the taxpayer. Missed deadlines were the next big reason for case losses. A document filed late in court, an incomplete court file, or evidence presented to the revenue authority after the tax audit period are formally closed have cost taxpayers billions of shillings. Taxpayers should approach transactions with a tax lens and assume that their internal assessment will be challenged.
What tax heads were experiencing more litigation?
Of the matters assessed, we found that VAT is both the most litigated tax head and where taxpayers lose most. The taxman secured favorable outcomes in 59 per cent of the 1,211 matters, mostly on denied input tax and contested exemptions. More than a third of the rules are procedural, the machinery of assessment, objection, timelines and the burden of proof. On the fringe are capital gains tax assessments, tied to gains in the value of qualifying assets, such as land and unlisted shares, transferred for speculative purposes.
From a transfer pricing perspective relating to multinationals operating in Kenya, we have seen KRA challenging controlled transactions on loans or intellectual property between related parties and that ought to have been at an arm’s length price.
How much money is at stake?
The largest dispute assessed was a Sh22.8 billion, 16-year legal matter involving excise duty classification, VAT and corporation tax. With an additional Sh3 billion penalty tied to this matter, it became an existential threat for the company. In another high-profile matter, the tax agency demanded Sh22 billion from a tobacco company, exemplifying why companies in high-excise sectors must settle tax classification early and in writing and not litigate late. Another Kenyan company operating internationally lost a Sh7.18 billion case since income tax earned from activities outside Kenya were, contrary to its assertion, taxable locally.
Drawing from these insights, how exactly does the Africa Tax Terminal intend to address the gaps you uncovered?
Think of it as a tax watchman that never sleeps. Every day, its fed with new court decisions, KRA notices, and any relevant changes to taxation laws in the country. The information comes only from verified sources, including Finance Acts, Tax Amendment laws, and Kenya Gazette notices. As earlier indicated, we mapped over 6,000 documents and over 74,000 tax rules and deployed several AI tools to manage this large trove of information. One on-demand tool answers your tax questions in plain language, with appropriate references to applicable legal provisions and decisions, another tracks the new court and tribunal decisions that have been verified and inputted by our team.
A different tool maintains a personal calendar for users based on KRA filing deadlines applicable to them, while the fourth runs continuous health checks to identify potential risks and compliance gaps. We have also embedded a proactive alert system that keeps finance teams informed of their tax account status through timely notifications and periodical reminders, while another a monthly reporting tool generates insights on the current tax landscape that they can be presented to the Board and Management to support decision-making and strategic planning.
In today’s evolving landscape, the firms that will stay ahead are those that can answer a tax question against the actual Kenyan record in minutes, keep the evidence that answer rests on, and do it again when the next time the law changes. This database gives finance teams the confidence to rely upon their tax judgement of commercial transactions and reassure boards and shareholders that their business’ value will be preserved.
Is AI replacing tax advisers?
No. The technology reads the information experts have fed it. Information that qualified professionals have assessed. Our system does not go randomly trawling the Internet like your usual Google search. A general chatbot draws on the whole Internet and can sound confident while being wrong. For avoidance of doubt, the terminal does not give formal legal opinions, file returns, or make decisions for you.
So, what happens when a KRA notice lands on the desk of a finance director?
The finance team can upload it and the terminal will flag what is at stake, including applicable deadlines and past decisions on similar issues. This quickly turns a worrying letter into a clear to-do-list. A finance director will hear about a relevant tribunal ruling within hours, not months later from auditors. Finance directors can run a tax health check and where expert review is required, our tax specialists can validate the findings and issue a certified report within 48 hours.
Speaking of data, what measures have you put in place to safeguard integrity of the information in the system?
Data integrity is especially critical. We have put in place various measures, from the users’ side of the portal, as well as the backend to ensure that logins are secure, that data is encrypted, and that data from different clients never interacts. Also, we have taken appropriate hosting measures. I must stress that client data is not being used to train the AI models.
Lastly, when are you launching it and are there plans for expansion outside Kenya?

Comments
No comments yet. Be the first to share your thoughts.