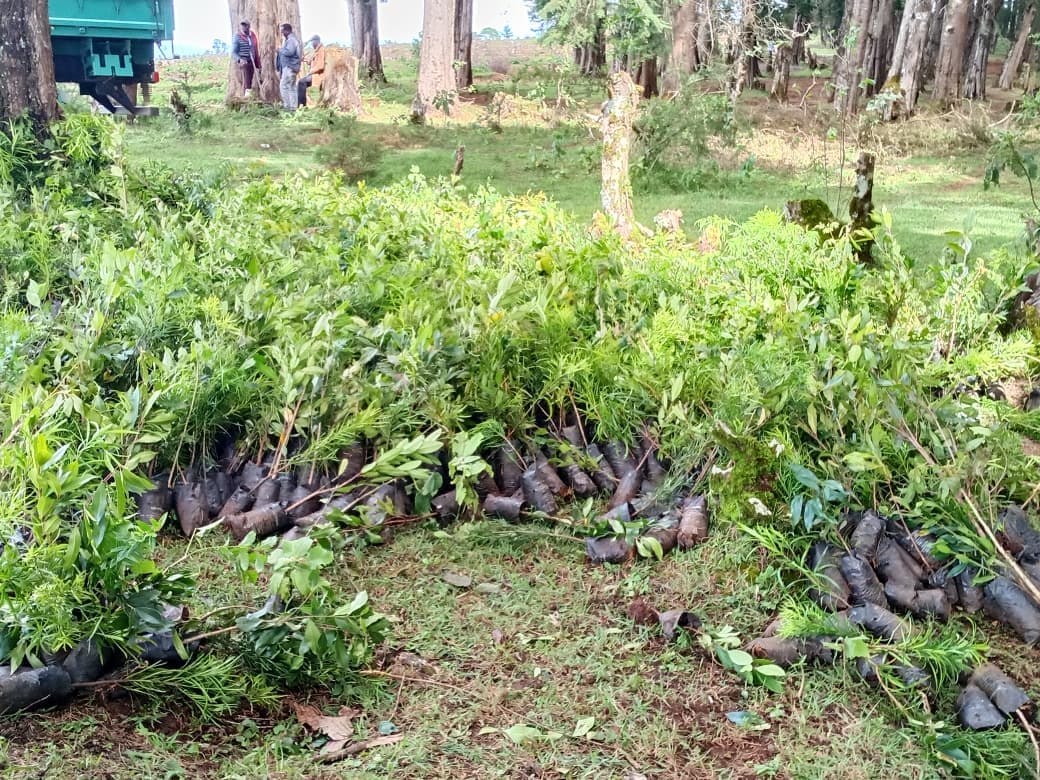
African governments are deliberately developing new ways to finance the protection and restoration of forests, providing practical examples of how forest finance can move from just models to delivery at scale.
According to a Progress Report by the Forest Finance Roadmap launched on Friday, September 25, at the Forest and Climate Leaders’ Partnership (FCLP) Forest Finance Day during Climate Week in New Yorl City, African governments are quickly warming up to forest finance. But the pace and scale of change remain below what is required to halt and reverse forest loss by 2030.
Aim is to reform economics of forest protection across the planet, and close an estimated $66.8 billion annual forest finance gap.
Forests currently receive less than one percent of global climate finance despite offering around one fifth of the world’s cost-effective mitigation potential.
Emelyne Cheney, Director, FCLP Secretariat, says, one year on, the Forest Finance Progress Report provides a clearer picture of where finance is flowing, and where it is not.
Cheney adds that clarity matters, and starts with not only closing the forest finance gap but understanding its scale and where the gaps lie.
“Pressures on forests are intensifying and the solutions are clear, but they need sustained political attention and investment at scale to turn into action. Forests cannot be an afterthought in the international climate agenda – they need to remain at the centre of it,” says Cheney.
Africa’s forests matter because the continent is home to approximately 663 million hectares of forest – 16% of the world’s forest area. Protecting and restoring these forests is critical to the global commitment to halt and reverse forest loss by 2030, as well as to livelihoods, biodiversity, food and water security and climate resilience across the continent.
Kenya has secured at least $229 million in new external finance for forest- and landscape-based economic development, principally through a $200 million World Bank operation and a $29.2 million Green Climate Fund Lake Region grant.
Kenya also increased its forestry budget by approximately $38.7 million in FY2025/26 and maintained an allocation of about $143.8 million for FY2026/27.
Ethiopia is investing 0.5-1% of its annual federal budget – approximately $40-80 million a year – in forest and landscape restoration, against an estimated $4.3 billion annual cost from land degradation. Its nationally owned financing mechanism has helped attract hundreds of millions of dollars in international concessional finance and co-financing.
Nigeria has also embarked on creating a government-led framework to align development partners, financial institutions, philanthropy and private investment behind national forest, climate and biodiversity priorities. Its Securing Nigeria’s Forest Future Country Package plan is expected to launch internationally at COP31.
Other African countries are also bringing forest outcomes into mainstream financial policy. Côte d’Ivoire has launched Africa’s first Sustainability-Linked Finance Framework and secured West Africa’s first EUR 433 million sustainability-linked sovereign loan, while Uganda is piloting an approach to integrate forest and agricultural resilience into sovereign debt and credit analysis.
As Ethiopia prepares to host COP32 in Addis Ababa in 2027, these developments give African governments an opportunity to help shape the global forest finance agenda from the position of countries demonstrating solutions, not simply seeking finance.
Gabon is also going big in forest protection. It is a partner country of the Central African Forest Initiative (CAFI), which is developing approaches that link finance directly to forest and ecosystem outcomes.
CAFI’s growing Payments for Ecosystem Services pipeline currently totals US$290 million and aims to mobilise up to US$2 billion by 2035 from domestic and international public and private sources across the Congo Basin.
Kenya, Ethiopia, Nigeria and Gabon show how African-led investment, domestic finance, results-based finance and country-led investment can help change the economics of forest protection.
“We must strengthen the enabling environment for private investment, blended finance, carbon finance and ensure these investments translate into real benefits like livelihoods linked to conservation, commercially viable forest value chains, meaningful participation for women and young people in the green economy,” Mr. Balarabe Abbas Lawal, Minister of Environment, Federal Republic of Nigeria, said.
Taken together, the examples show that the mechanisms exist and African governments are beginning to put them into practice. The test now is whether they can attract and deploy finance – and deliver benefits for forests, economies and communities – at the scale and speed required by 2030.
Comments
No comments yet. Be the first to share your thoughts.