Kenya’s economic growth is projected to slow to 4.8 percent in 2026, down from an earlier forecast of 5.1 percent, according to NCBA Bank’s revised Economic Outlook.
The lender warns that mounting external shocks and domestic pressures are weighing heavily on the country’s macroeconomic horizon.
“The year 2026 has been characterized by a convergence of shocks, including the crisis in the Middle East, the ongoing Russia-Ukraine conflict, sudden monetary tightening in key economies, and sovereign bond market volatility,” said NCBA Group Managing Director and CEO, John Gachora.
Mr. Gachora adds that while the economy has remained resilient, it lacks the capacity to absorb successive shocks. For him, the immediate priority is twofold: safeguarding hard-won gains while simultaneously accelerating growth
Looking ahead to 2027, Gachora expects growth to oscillate within a wider range of 4 to 5 percent, a volatility he attributes to global political tensions, erratic commodity prices, changing weather patterns, and the upcoming general elections.
According to National Treasury and Economic Planning Cabinet Secretary (CS) John Mbadi, economic growth has been averaging 5 percent between 2022 and 2025, with inflation remaining within the target range at 7.3 percent in October 2026, even as the shilling continue to strengthen at an average of about Ksh129.9 against the US dollar and foreign exchange reserves rising to $14.9 billion, equivalent to 6.1 months of import cover
CS Mbadi noted that sustaining the gains would require continued fiscal discipline, more efficient public spending, stronger revenue mobilisation and prudent debt management, particularly as rising expenditure pressures, including domestic debt interest payments and pension obligations, continue to constrain available fiscal resources.
“We project economic growth of 5.1 percent in 2027, with inflation remaining within target and the shilling maintaining stability. Safeguarding these gains will require sustained fiscal discipline, improved revenue mobilisation and better management of public expenditure. We are also undertaking reforms to improve access to credit, including transparent, risk-based credit pricing anchored on KESONIA, modernised payment systems and the transformation of the Credit Guarantee Scheme to unlock more lending to SMEs,” said Mr Mbadi.
Beyond fiscal policy, the forum highlighted the need to strengthen Kenya’s productive capacity, expand exports and attract investment into sectors capable of driving long-term economic growth. While gains in agriculture, manufacturing and other areas point to improving economic activity, sustaining this momentum will require greater investment, improved productivity and a more enabling business environment.
Supporting the view, Dr David Ndii, Chairperson of the President’s Council of Economic Advisors, pointed to improving activity across agriculture, manufacturing and other sectors, noting that gains in milk production, sugar output, coffee production and vehicle registrations reflected stronger underlying economic momentum, some of which was not yet captured in official statistics.
Ndii explains that Kenya’s next phase of growth will depend on steering investment and improving productivity in sectors that generate jobs, expand exports and create economic value.
“We are tracking an investment pipeline of approximately $45.7 billion across infrastructure, manufacturing, agriculture and ICT, alongside a proposed National Infrastructure Fund expected to mobilize $10 billion. Major opportunities, including the proposed $24 billion Lamu Port and oil complex investment, could further strengthen export capacity, infrastructure development and regional integration,” he says.
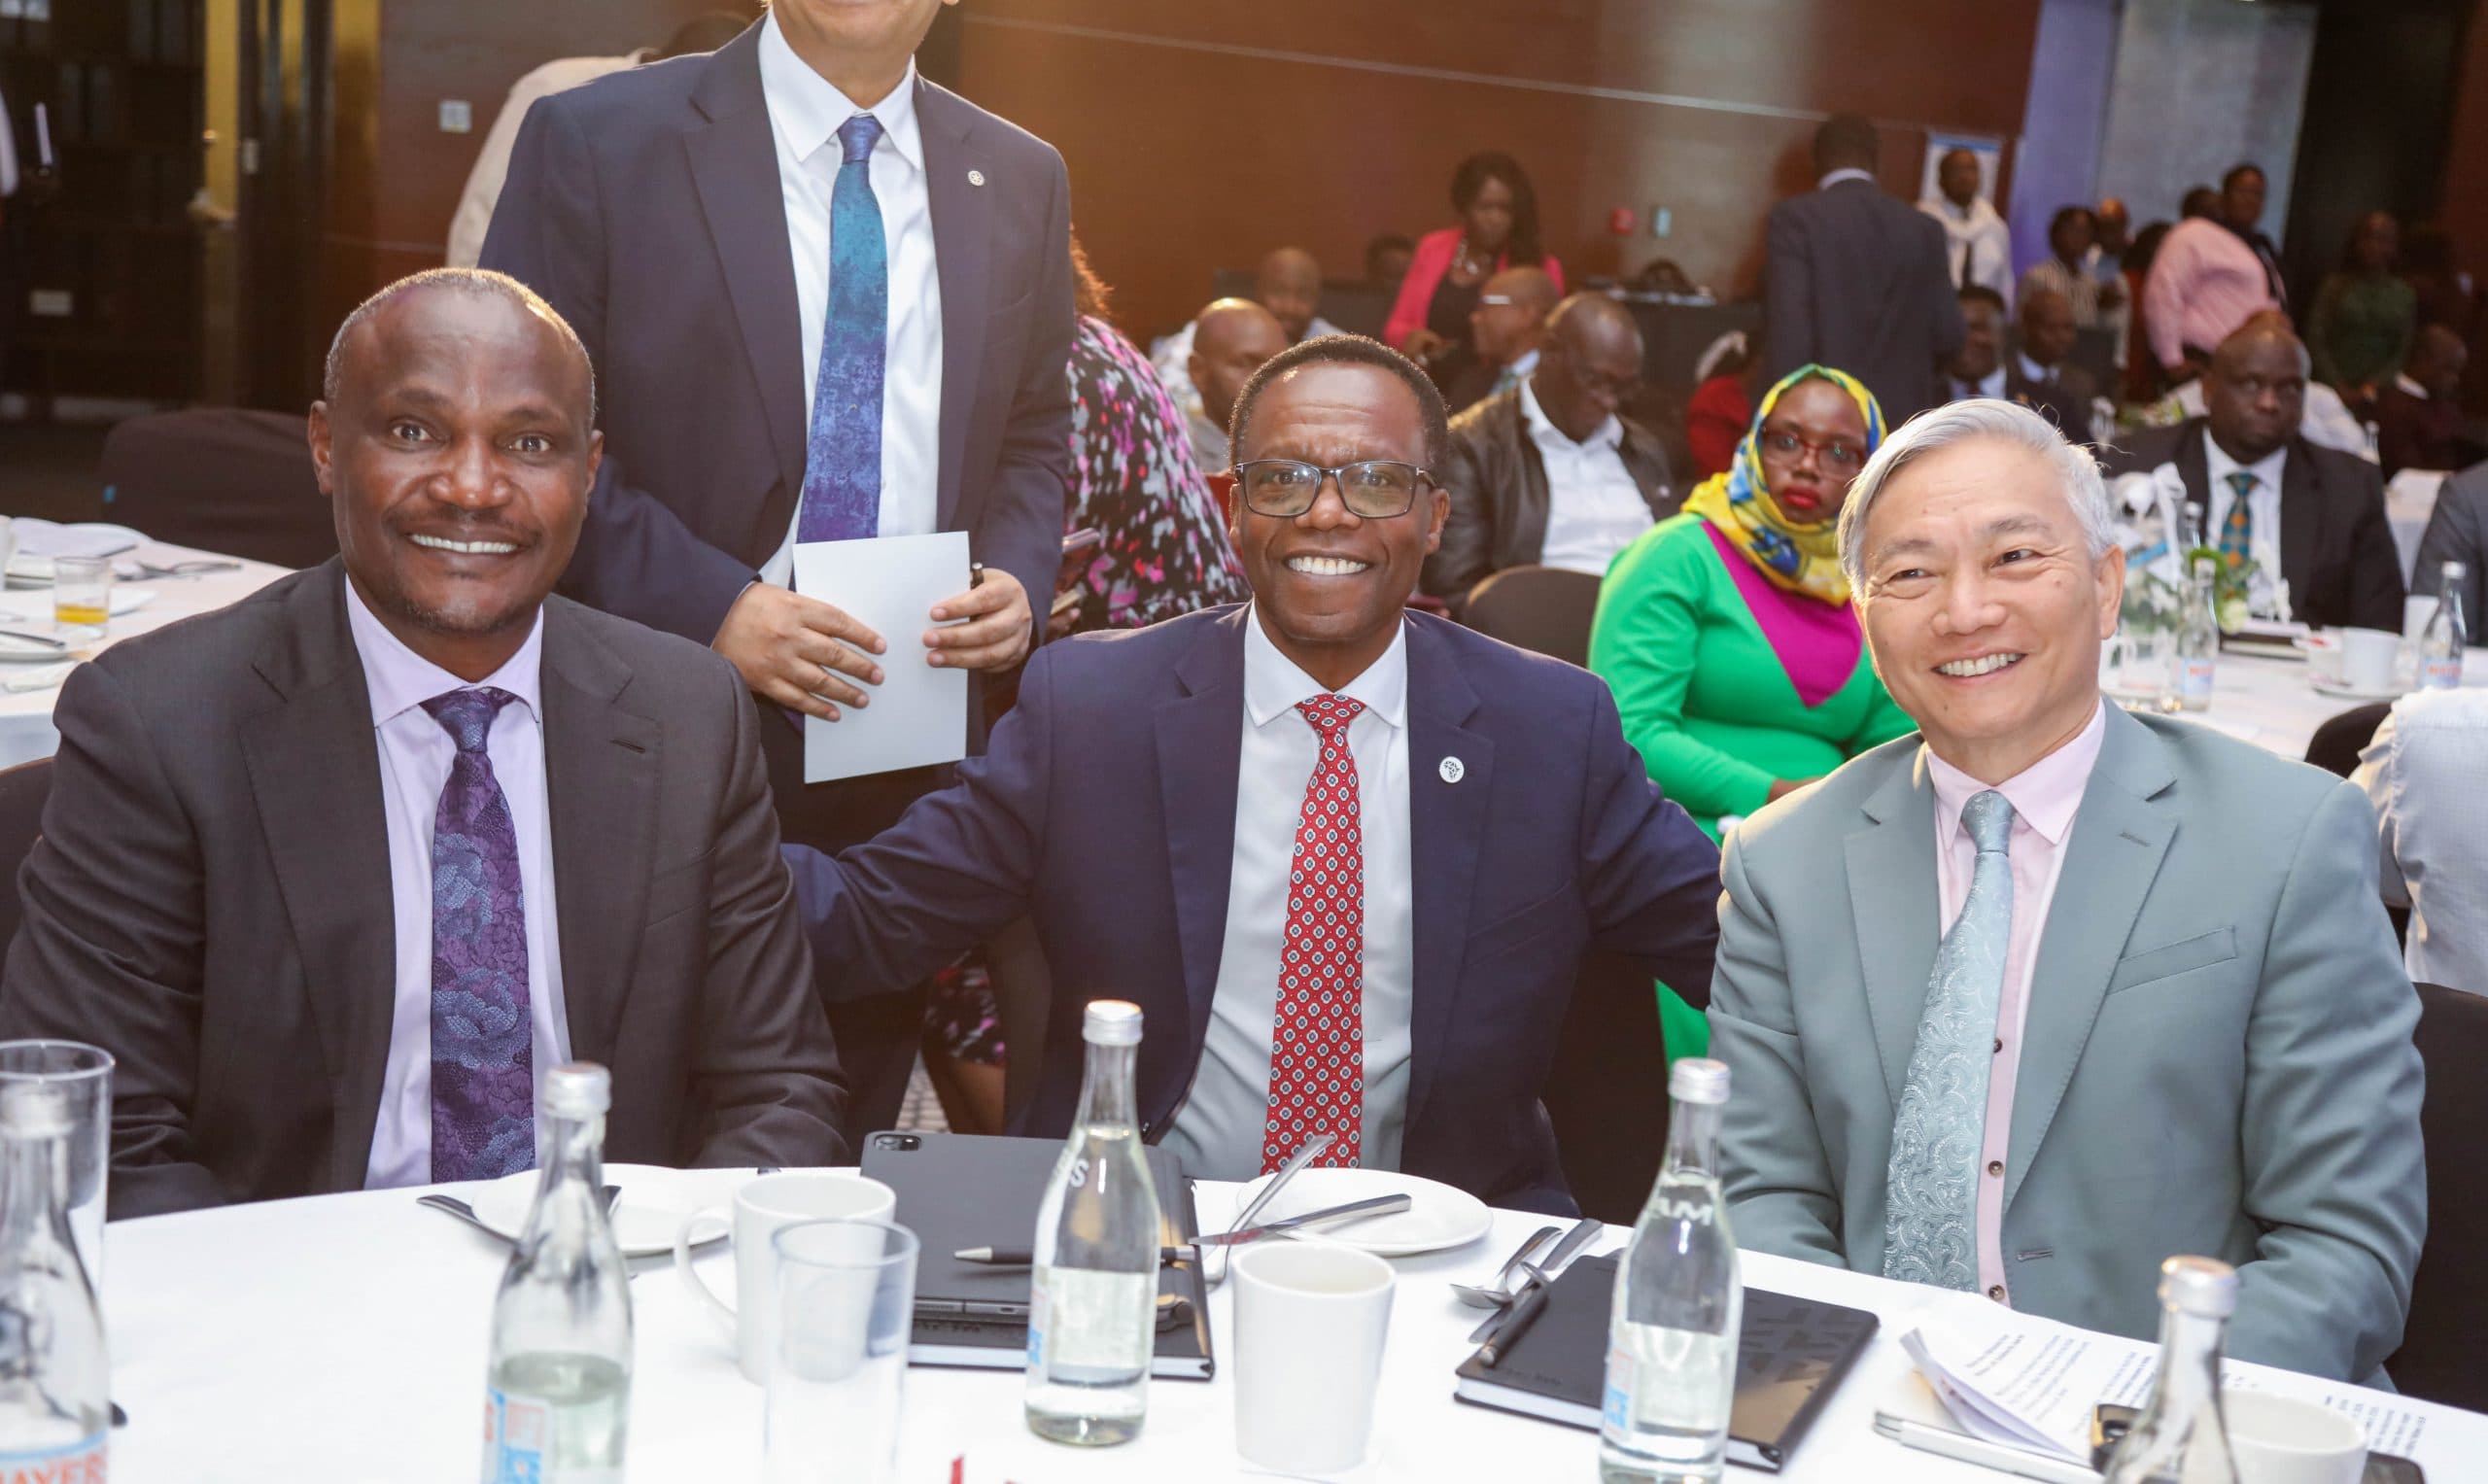
This comes as experts at the NCBA Economic Forum 2026, held today, on Tuesday, November under the theme “Sustaining Economic Resilience, While Safeguarding Policy Gains in 2027” say that while the economy has increasingly shown resilience, its capacity to absorb further shocks is still a key concern.
The event was graced by CS Mbadi; World Bank Division Director for Kenya, Rwanda, Somalia, and Uganda Dr Qimiao Fan; and Dr David Ndii, Chairperson of the President’s Council of Economic Advisors (CEA), among others.
Looking ahead, industry leaders noted that geopolitical tensions, commodity price volatility, adverse weather conditions and tighter global financial conditions would continue to test economic resilience in 2027. They emphasized the need for sound economic policies and stronger collaboration between government, the private sector and development partners to safeguard macroeconomic stability, unlock investment, strengthen productive capacity and sustain job creation.
Comments
No comments yet. Be the first to share your thoughts.