By Anton Gillis, co-founder and CEO of HAMAC (Hospitality Asset Management Company)
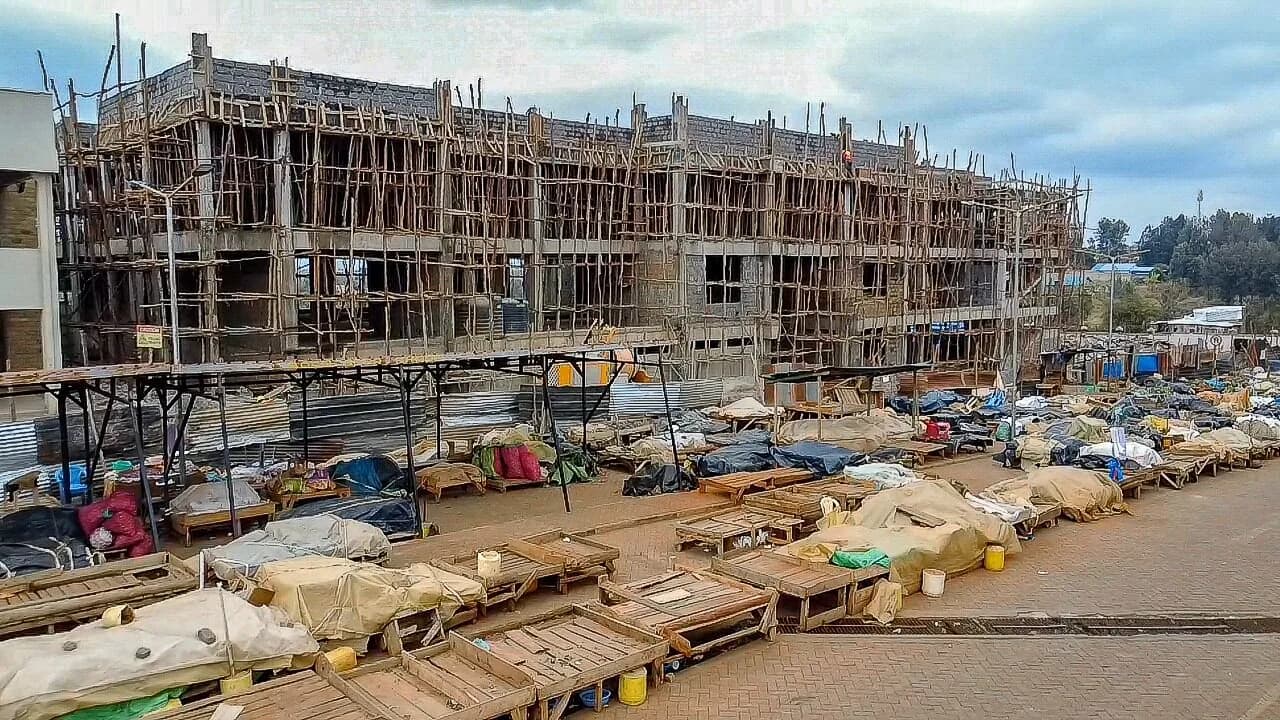
Kenya has one of the most credible hotel development pipelines on the continent. W Hospitality Group’s 2026 pipeline report counts 6,190 branded rooms across 35 hotels, and close to 80% of those rooms are already under construction. That second number matters more than the first. It is roughly double what Nigeria is showing, and it means these are not press releases. They are buildings. Most of them will open inside two years, in Nairobi, on the coast and at the safari gateways.
Which raises a question the industry is not asking loudly enough. Every hotel valuation conversation starts in the same place. Capex plans, revenue management systems, brand affiliation, the flag on the building. Owners obsess over these levers because they are visible, measurable and easy to put in a deck. What rarely gets the same airtime is the thing that actually determines whether any of that capex or brand equity translates into performance: the people running the property every single day. Too much of this industry still treats people development as an HR nicety rather than what it actually is, a direct lever on asset value.
I manage hotel assets in South Africa, not in Kenya, so let me be careful about what I am claiming. The specifics of the Kenyan labour market are not mine to lecture anyone on. But the economics of staff turnover are not country-specific, and neither is the mistake owners make about them.
Turnover is not an HR line item, it is a value leak
Research out of Cornell’s School of Hotel Administration has long put lodging turnover at roughly 60% of frontline staff and 25% of managers a year, with each departure costing close to $6,000 for a frontline role and nearly $10,000 for a manager, mostly through lost productivity while a replacement finds their feet. That is not a soft cost. That is money leaking out of the property every time someone walks out the door because the pipeline behind them was never built properly.
At HAMAC we surveyed South African hoteliers this year, and the results were blunt. Seventy-seven percent named human capital as one of the biggest threats to business sustainability. Almost 70% were dissatisfied with the competency of graduates entering the industry, with leadership and soft skills the two largest gaps. Labour came out as the single biggest pressure on margins, ahead of electricity and food. And 46% said they would prioritise investment in people if the basic infrastructure around them were reliable enough to let them.
I do not offer that as Kenyan data. I offer it because when Kenyan operators describe their own recruitment and retention problems, they describe the same structure. Kenya has spent fifty years building one of the best hospitality training institutions in Africa in Kenya Utalii College, with more than 60,000 graduates behind it, and the industry still says the pipeline does not match what properties actually need. Academic work on the Kenyan skills gap keeps landing on the same diagnosis: training that is supply-driven rather than demand-driven, with technical, service and management competencies arriving unevenly. An institution that good producing a mismatch that persistent is not a training failure. It is a coordination failure between owners, operators and educators, and owners are the party least often in the room.
Guest experience is the scoreboard, and it is a people scoreboard
Here is the bit owners keep missing. Guest experience scores are not a marketing metric that lives somewhere separate from the balance sheet. They feed rate integrity, they feed repeat bookings, and over time they feed RevPAR against your competitive set. A property with high turnover does not deliver an inconsistent guest experience by accident. It delivers it because the person checking a guest in this month has three weeks of experience instead of three years. Guests notice. Review platforms record it. Rate strategy suffers because of it.
That matters more in Kenya than in most markets, because of who is arriving. Kenya took an estimated 7.9 million visitors in 2025, of whom 5.2 million were domestic travellers, and Africa was the single largest international source region at 47% of arrivals. Regional and domestic guests are repeat guests. They come back four times a year, not once a decade. Consistency is the entire proposition, and consistency is a function of retention.
Which is why the question asset managers should be asking operators is not whether they meet brand training standards. Most will. The question is whether that training translates into real career pathways, real retention, and real capability on the floor, or whether it is box-ticking to satisfy a compliance audit. Turnover rate against the local market, time to competency for new hires, internal promotion ratios: these are numbers that belong in the same report as occupancy and GOP margin, not buried in an HR appendix nobody reads.
Kenya has close to 4,900 rooms going up right now, into a market with more demand behind it than it has had in a decade. The properties that get serious about this will hold an advantage that a bigger capex budget cannot buy on its own. The ones that keep treating people as a cost line will keep bleeding value, quietly, review by review, booking by booking, until someone finally asks why the numbers do not add up.
Comments
No comments yet. Be the first to share your thoughts.