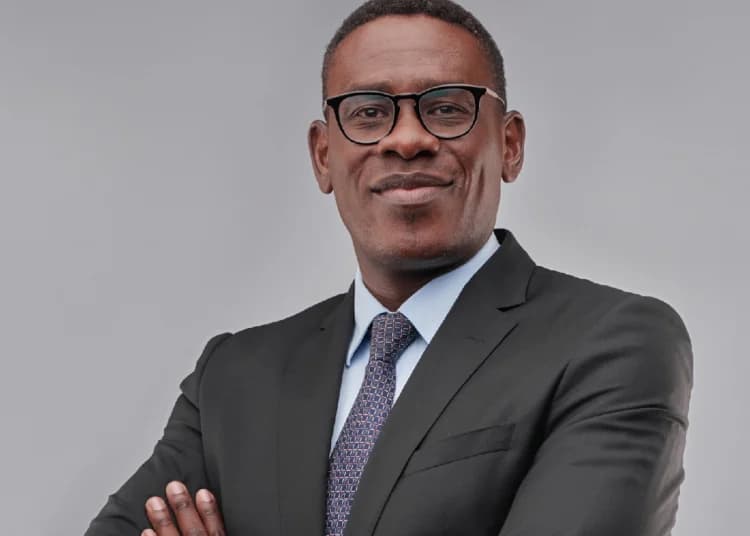
NCBA Group has lost Eric Muriuki, where he ran the LOOP digital banking business, to join Absa Group as Managing Executive for Pan-African Growth Strategy, Platforms and Digital Ventures. LOOP Digital Financial Services was NCBA’s neobank, a bank that operates mostly through an app.
Muriuki ran this NCBA app and introduced it into other markets in the region. This appears to be what motivated Absa to go after Muriuki, to drive its expansion ambitions across Africa.
Muriuki’s new title at Absa Group covers three things: growth strategy across Africa, platforms, and digital ventures. That is a wide remit, but it fits someone whose track record is building products that attract very large numbers of small customers rather than a small number of large ones.
The former NCBA digital genius will start his new role at Absa this month and will be based in Johannesburg, South Africa.
Muriuki is the guy behind M-Shwari, Fuliza and the M-Pesa trust account model-products that gave NCBA 31.9% of its pre-tax profit. Fuliza alone did KSh 1.24 trillion in loans in 2025.
NCBA has yet to name Muriuki’s replacement at LOOP, although Bryan Kariuki, who was brought in as Chief Product Officer at LOOP is a front runner.
Eric Muriuki began his fintech career at Citi in Kenya in 1999 as a Business Systems Manager and stayed almost five years. In 2004, he moved to Co-operative Bank of Kenya as a Business Change Manager, which he did until mid-2007.
Thereafter, he moved to NCBA Group where he worked for 19 years and 4 months, in three roles: Programme Director, Enterprise Transformation – July 2007 to August 2012. General Manager, New Business Ventures – August 2012 to September 2019. Group Director, Digital Business and CEO of LOOP DFS – October 2019 until the move to Absa
NCBA Merger with CBA marked the beginning of NCBA Group
NCBA in its current form only exists since 2019, when NIC Group and Commercial Bank of Africa merged. The earlier years of his career were spent at the legacy bank under the NCBA heading.
Muriuki helped design the trust-account structure that allowed Safaricom to issue electronic money through M-PESA with regulatory approval. This was important because Safaricom is a telecom company, not a bank.
The trust arrangement allowed NCBA customers’ money to be held and transferred legally, and became the foundation for mobile money in Kenya.
Later, while working on his MBA thesis, Muriuki’s work led to the birth of M-Shwari, a mobile savings and micro-loan product that does not require physical collateral.
He also engineered the launch of Fuliza, a mobile overdraft service, one that allows one with less cash in their M-PESA account to complete a transaction. Fuliza covers the shortfall and you repay it later. It has since become one of Kenya’s most widely used credit products.
So Absa is poaching the brains behind NCBA’s digital lending platform to build its Pan African digital platform “Absa Next”
The latest moves within Kenya’s banking space involves the move by Abdi Mohammed, who resigned from Absa to join I&M Bank as CEO.
Talent poaching in Kenya’s banking business is taking place as the country becomes a battleground for cross-border banking expansion in Africa, attracting interest from Nigerian, South African and other international groups.
Following the acquisition of National Bank of Kenya by Nigeria’s Access Bank, South Africa’s Nedbank made an offer in January 2026 to acquire 66% of Kenya’s NCBA Group.
NCBA ranks 11th in East Africa this year, with $684m in capital. A successful transaction would therefore give Nedbank control of a substantial Kenyan institution.
The interest of Access and Nedbank illustrates Kenya’s advantages.
Kenya has a relatively developed capital markets, wide use of digital payments, strong regional commercial links and an established banking culture.
Outside entrants do face formidable local competitors, with Equity, KCB and Co-operative Bank remain the regional leaders.
Comments
No comments yet. Be the first to share your thoughts.