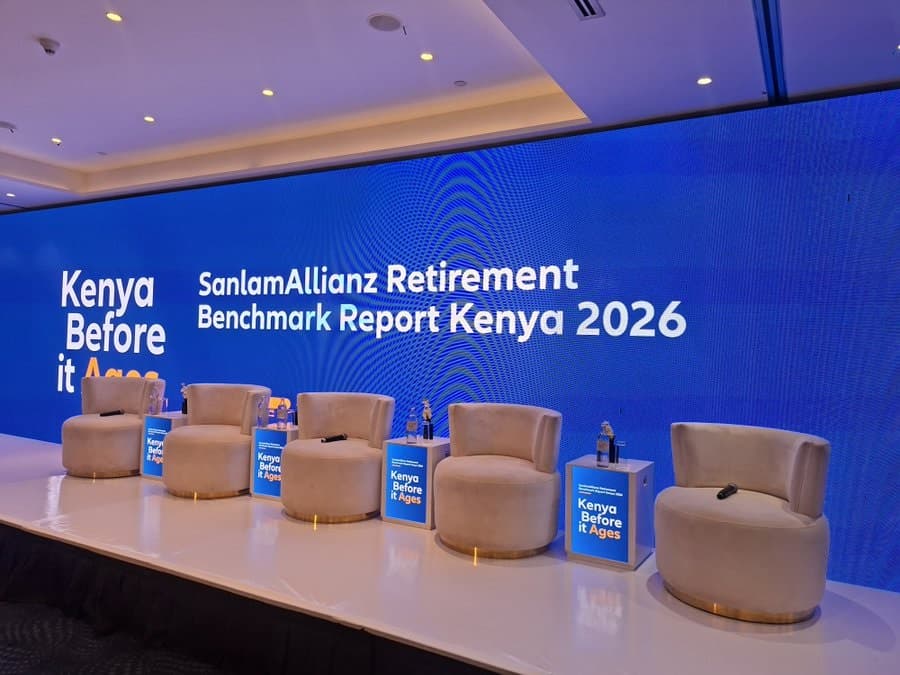
Despite a high level of awareness regarding the importance of financial planning, 7 in 10 working Kenyans are not on track to secure a comfortable retirement. Everyday economic realities, caretaking obligations, and early cash-outs continue to erode the nation’s long-term savings pool.
The findings come from the inaugural SanlamAllianz Kenya Retirement Benchmark 2026, titled Kenya Before It Ages. The nationwide study underscores a fundamental disconnect in the country’s financial ecosystem: while basic financial literacy is high, household budgets are increasingly stretched, leading to systemic savings leakage when workers transition between jobs.
The report highlights that immediate family obligations and macroeconomic pressures routinely take precedence over future planning.
1. Family & Household Demands
44% of respondents cite routine living costs as the primary barrier to saving, while 37% point to low or irregular income, and 24% struggle with debt obligations. Only 4% attribute their lack of retirement savings to a lack of trust or understanding of financial products.
2. The Squeeze on Young Earners
Supporting dependants reduces saving capacity for 62% of respondents. Furthermore, 39% admit they could survive for two months or less on existing funds if their primary income stopped today. Over the past year, 23% of workers dipped into savings or scaled back retirement contributions, a figure that jumps to 29% among adults aged 20 to 39.
One of the study’s most critical findings is the widespread practice of liquidating pension funds during career transitions. Among workers who left a job or business holding retirement funds, 53% withdrew at least a portion of their savings, while 26% liquidated their entire balance. Only 32% preserved or transferred their full balance into another vehicle.
While one-third of those who withdrew cash reinvested it into starting a business or farming venture, the long-term cost remains steep. Although 65% understood the immediate financial impact at the time of withdrawal, 53% ultimately expressed regret, with one in five reporting they received no financial guidance or offboarding advice during their employment transition.
What Happens to Pension Funds Upon Job Exit?
Full Transfer/Preservation ████████ 32%
Partial Withdrawal █████████████ 53%
Total Liquidation ██████ 26%
Later Expressed Regret █████████████ 53%
Beyond immediate cash pressures, many Kenyans are saving without a defined retirement income target:
- Unclear Targets: 20% of active working contributors do not know their current accumulated balance, and only 29% know how much monthly income they will actually need after retiring.
- Low Product Awareness: 45% have never heard of income drawdown products, despite 51% expressing a desire for a guaranteed monthly income for life.
- Healthcare Deficits: 53% have no funded plan to cover post-retirement medical expenses.
- The Drive to Keep Working: Demonstrating a shift in traditional retirement perception, 88% of respondents state they plan to continue working or running a business even if their retirement payout is sufficient to live on.
As Kenya’s economy expanded by 4.6% in 2025, the Kenya National Bureau of Statistics reported that the informal sector accounted for 87.2% of all new jobs. Within this segment:
- 39% report fluctuating monthly income.
- 51% prefer contributing to retirement schemes via mobile money platforms.
However, the rapid digitization of financial services presents new vulnerabilities. 45% of respondents report having lost money or personal information to digital financial scams, a number that climbs to 54% among younger demographics. When evaluating potential pension products, consumers rank backing by a trusted regulator or institution as their primary criteria.
Comments
No comments yet. Be the first to share your thoughts.