By Shehryar Ali, senior vice president and country manager for East Africa and Indian Ocean Islands at Mastercard
NAIROBI, Kenya, Sept 23 – For years, the conversation in East Africa about digital commerce has been about access. Connecting people to mobile money, enabling businesses to accept digital payments and bringing more consumers into the formal financial system.
That progress has created one of the world’s most dynamic digital payment environments. East Africa is a leader in mobile payments globally and continues to evolve as consumers move between mobile money, cards, digital wallets, apps and online marketplaces.
What comes next is a different kind of challenge. As more commerce moves online, trust is increasingly becoming the deciding factor of whether people and businesses participate and transact online. The question is no longer whether a payment can be made digitally. It is whether the ecosystem behind that payment can make the transaction both secure and seamless.
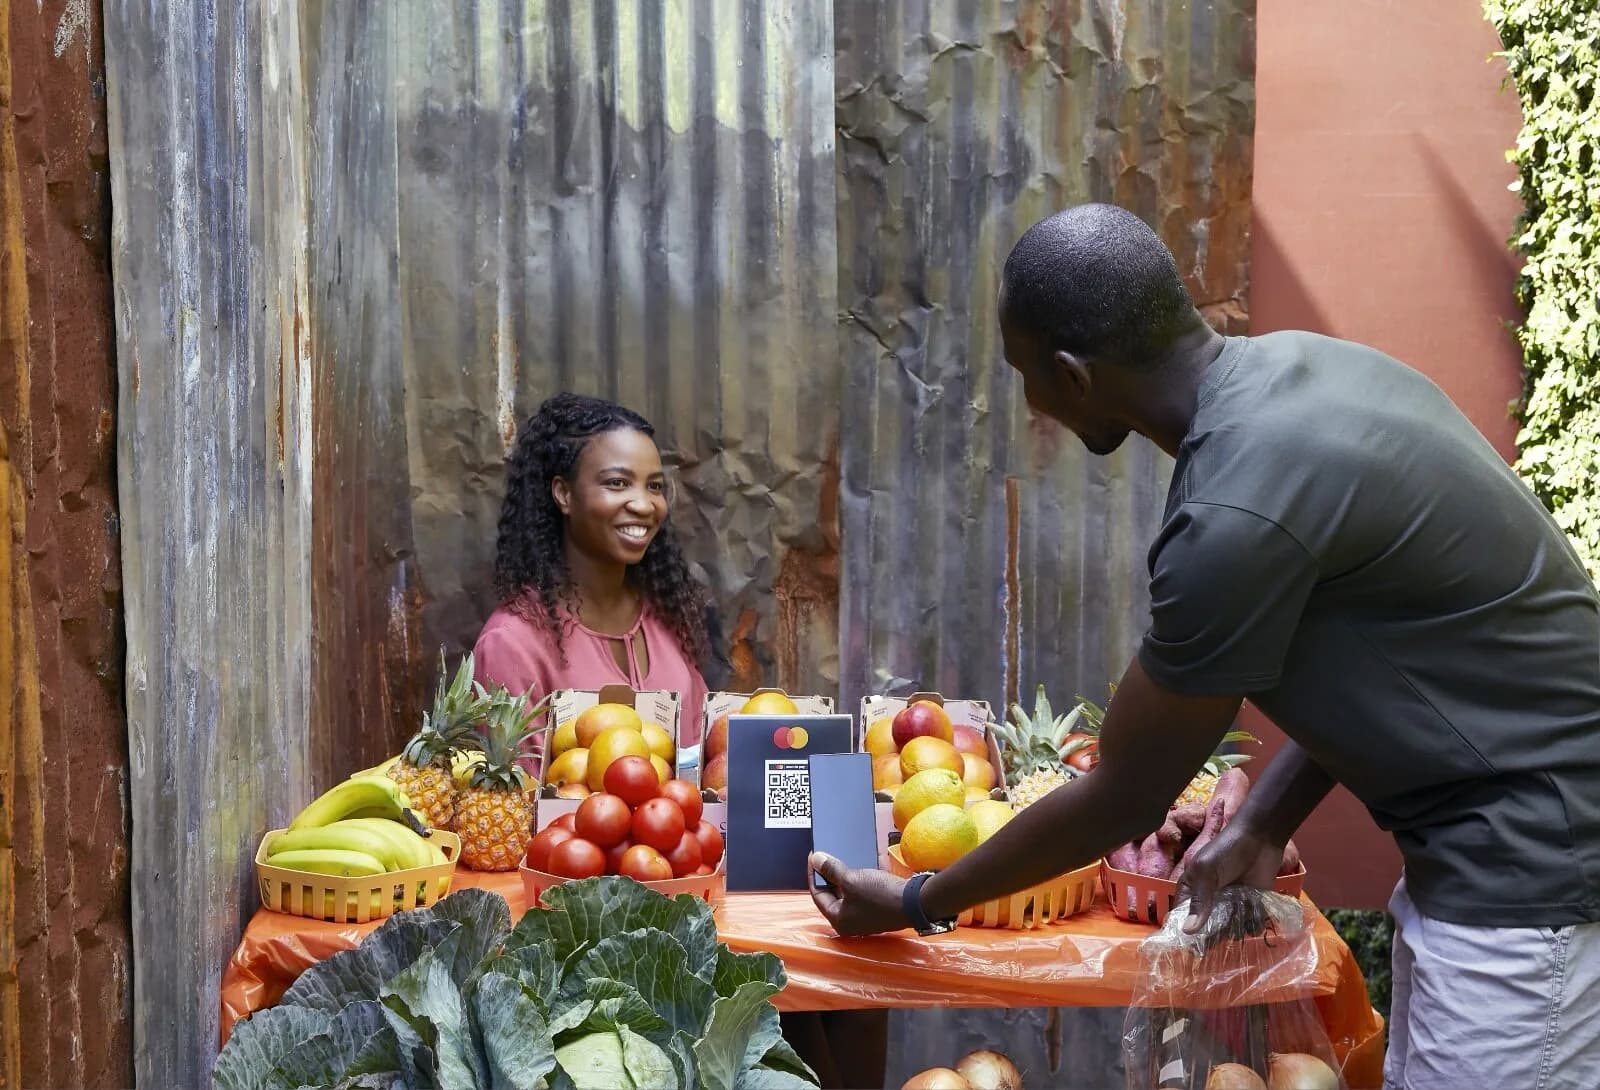
Kenya shows where the region is heading. Mastercard’s 2026 SME Confidence Index found that 95% of Kenyan SMEs accept mobile payments and 39% accept online payments, while 70% expect their revenues to grow over the coming year. Those numbers demonstrate the importance of digital tools today and the ambition businesses must have to scale tomorrow. That growth creates an opportunity. It also creates a responsibility.
When the card isn’t there, trust has to work harder
A card-not-present transaction occurs when the physical card is not presented at the point of purchase. Instead, payment credentials are transmitted digitally through an online checkout, app, marketplace or another digital environment.
This simple change has transformed commerce. A consumer in Nairobi can purchase from a business they have never visited. A small business in Kampala can reach customers beyond its physical location. A customer in Dar es Salaam can pay for a service from a smartphone without ever interacting with a physical point of sale. But this access and convenience also mean that the trust signals behind every transaction need to be assessed digitally. The ecosystem must determine whether the payment credentials, the device, the merchant, the customer behavior and the transaction all make sense together, often within milliseconds.
Mastercard data shows that 70% of card-related fraud occurs on card-not-present transactions, highlighting why the security of digital commerce has to evolve alongside its growth.
TransUnion reported that 2.3% of transaction attempts involving consumers in Kenya in 2025 were suspected of digital fraud. Among Kenyan consumers who reported losing money to digital fraud, 39% said third-party seller scams on legitimate websites were responsible. This highlights how much of the risk sits outside the payment credential itself. It can sit with the merchant, the device, the identity or the wider context in which a transaction takes place.
The East African Community has recognized this challenge through its regional e-commerce agenda, which focuses on creating an enabling environment for cross-border digital trade while strengthening consumer protection, digital identity and trust in online transactions. That work matters because digital commerce does not stop at national borders.
Security Should Not Mean More Friction
As digital commerce becomes more embedded in everyday life, security needs to become more sophisticated and less visible at the same time. The goal should not be to make every transaction feel like a security check. It should be to use technology and intelligence to identify genuine risk while allowing legitimate commerce to keep moving.
Tokenization is one example. Instead of exposing the underlying card number during a digital transaction, Mastercard tokenization replaces sensitive payment credentials with a unique digital token. More than four billion Mastercard transactions are tokenized globally each month, around 30% of Mastercard transactions worldwide, and Mastercard is targeting 100% tokenization of its online transactions by 2030.
Through its collaboration with MCB, Mastercard has launched Apple Pay in Mauritius, enabling Mastercard cardholders to make contactless payments with an iPhone or Apple Watch and pay in apps and online. The service uses tokenization to replace the card number with a device-specific token, helping protect payment details while keeping the payment experience seamless.
For the consumer, none of this is visible. The payment simply works. Behind the scenes, however, the credentials are better protected that they were. That is an important principle for East Africa: security should work inside the infrastructure rather than stand as one more barrier at the checkout.
The same principle applies to transaction intelligence. Mastercard’s Decision Intelligence uses AI and network insights to assess transaction context and help financial institutions distinguish legitimate activity from potentially fraudulent behavior. Rather than relying on one signal in isolation, the technology looks at patterns and relationships around the transaction to improve the precision of fraud decisions.
For card-not-present payments, that intelligence becomes particularly important because there is no physical card to provide a visible signal of legitimacy. The objective is not to treat every transaction as suspicious. It is to become better at understanding which transactions make sense, so that scrutiny falls where it belongs.
East Africa’s payment ecosystem is becoming more connected
Mastercard’s collaboration with KCB spans Kenya, Rwanda, Burundi, South Sudan, Tanzania and Uganda, supporting solutions that include e-commerce payments, cross-border remittances, QR payments and Tap on Phone. The collaboration reflects how payment ecosystems are increasingly being designed to operate across different channels and markets rather than around a single payment method.
In Kenya, Mastercard and Safaricom have expanded payment acceptance and cross-border remittance capabilities aiming to reach more than 636,000 M-PESA merchants, helping businesses participate more easily in digital and international commerce. In Uganda, Mastercard and MTN MoMo introduced the Virtual Card by MoMo, enabling customers to make online payments without a physical card or traditional bank account. In Tanzania, Mastercard and NMB Bank launched QR Pay by Link, allowing merchants to accept payments through QR codes and secure payment links without requiring a traditional point-of-sale device, while also incorporating Click to Pay for online checkout.
These are different solutions serving different needs, but they point in the same direction: digital commerce is becoming more connected, and the infrastructure behind it has to carry trust across the whole journey.
AI Is Changing the Fraud Equation
Artificial intelligence adds another layer to this. AI is already helping businesses personalize commerce, improve customer experiences and automate parts of the payment journey. At the same time, it is giving fraudsters new tools to create convincing websites, messages, identities and digital storefronts. That means consumers cannot rely on appearance alone.
A polished website does not make a merchant trustworthy, and a convincing message does not always come from a genuine business. A transaction that appears normal may look very different when assessed alongside other signals.
This is why the next generation of payment security needs to be increasingly contextual and predictive. Mastercard’s Merchant Trust Services is designed to extend that intelligence beyond the transaction itself. By combining Mastercard network insights with cyber and identity capabilities, external intelligence and analytics, it helps acquirers and payment service providers identify potentially fraudulent merchants from onboarding through ongoing monitoring.
This broader view of trust is particularly important as commerce becomes more distributed across websites, social platforms, marketplaces, apps and other digital environments. The question is no longer only, “Is this payment legitimate?” It is also, “Is the business on the other side of this payment legitimate?”
Trust Has to Be Built Across the Ecosystem
No single organization can answer that question alone. Consumers protect their credentials, verify who they are buying from and pay attention to what they authorize. Merchants keep their digital environments secure for the customers who use them. Financial institutions and payment providers strengthen fraud controls, and technology companies build security into the platforms where digital commerce happens. Regulators set the standards and frameworks that allow digital ecosystems to grow responsibly.
For East Africa, this collaborative approach is particularly important because the region’s strength has always been its ability to connect different parts of the financial ecosystem.
Mobile-money platforms, banks, fintech companies, merchants and technology providers are increasingly interconnected. Mastercard’s work across the region reflects that model, from linking mobile-money ecosystems to global payment rails, to expanding e-commerce acceptance, virtual cards and other digital payment capabilities.
The opportunity ahead is therefore bigger than preventing fraud. It is about creating the conditions for more people and businesses to participate in digital commerce with confidence.
The Next Phase of Digital Commerce Will Be Defined by Trust
East Africa does not need to be convinced of the value of digital payments. Consumers already use them every day, businesses accept them, and financial institutions and fintech companies are continually investing in new ways to make them more accessible.
The next challenge is ensuring that trust grows at the same pace as adoption.
That means protecting the credentials consumers use, giving financial institutions better intelligence to assess risk, and helping legitimate merchants establish trust. It also means designing payment experiences where stronger security does not translate into greater friction.
This is what the future of card-not-present payments in East Africa is about. The physical card may disappear, and the checkout may become almost invisible, but the technology and intelligence working behind the transaction will determine whether digital commerce can reach its full potential.
At Mastercard, we believe acceptance, security and privacy are the foundations of trust. When the card isn’t there, trust has to be.
Comments
No comments yet. Be the first to share your thoughts.