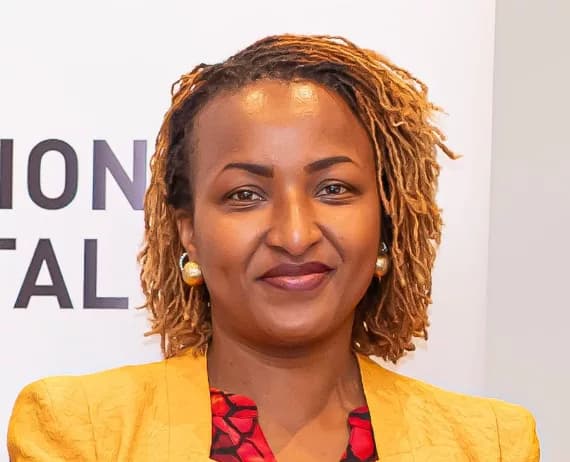
Tabby Mugechi, Senior Compliance and Ethics Manager, Tala /HANDOUT

For generations, we have relied on physical identity to tell us apart. The way we dress, walk, speak or even laugh can make us recognisable. But today, much of our lives no longer happen in the physical world.
We open bank accounts online. We apply for credit from our phones. We make payments, shop, communicate and access services without necessarily meeting another person face-to-face. As our lives become increasingly digital, another form of identity has emerged alongside our physical one: our digital identity. And protecting it is becoming just as important.
Think of it as your digital fingerprint. A digital identity is information that confirms who you are whenever you use an online service. It can include identification details, phone number or any other information used to verify your digital identity.
It becomes particularly important as more financial service providers move online. Otherwise, the same technology that makes financial services easier to access can also create opportunities for fraudsters.
Today, identity can be misused without anyone physically taking your identification document. Someone may use your personal information to create an account, access a service or obtain credit in your name. This is why the account-creation stage matters.
The latest TransUnion data shows that approximately 4.5% of account-creation attempts in Kenya in 2025 were suspected of digital fraud. Account creation was therefore one of the points in the consumer journey where fraud risk was particularly evident. This is where eKYC comes in.
Electronic Know Your Customer, or eKYC, may sound technical. But the principle is simple: verifying that the person opening an account or accessing a financial service is genuinely who they claim to be. When you accurately complete your eKYC information, you help a provider establish your identity and distinguish you from someone attempting to impersonate you.
As a digital financial services provider, Tala uses KYC identity verification to confirm customer identities and help protect customers and the business from fraud and other financial crimes. Its verification process requires a valid government-issued ID and a live selfie directly through the Tala app.
Financial services providers have a responsibility to invest in strong identity verification, fraud detection and consumer protection systems. Consumers have a role too. We need to become more conscious of the information we share, where we share it and why it is requested. That means identity protection must become part of how we think about everyday digital financial safety. As more transactions move online, trust becomes one of the most valuable currencies in the digital economy. We would not casually hand our identification document to a stranger. We should apply the same level of care to the digital information that increasingly represents us online.
Kenya’s digital economy will continue to grow, with more services and transactions moving online. That future will require more than convenience. It will require confidence. And building that confidence starts with something fundamental: knowing who is on the other side of the screen.
Our physical fingerprints have always helped tell us apart. Our digital identity is now helping do the same. The responsibility is to make sure that the digital identity belongs to us and stays ours.
Comments
No comments yet. Be the first to share your thoughts.